PEO Employee Benefits

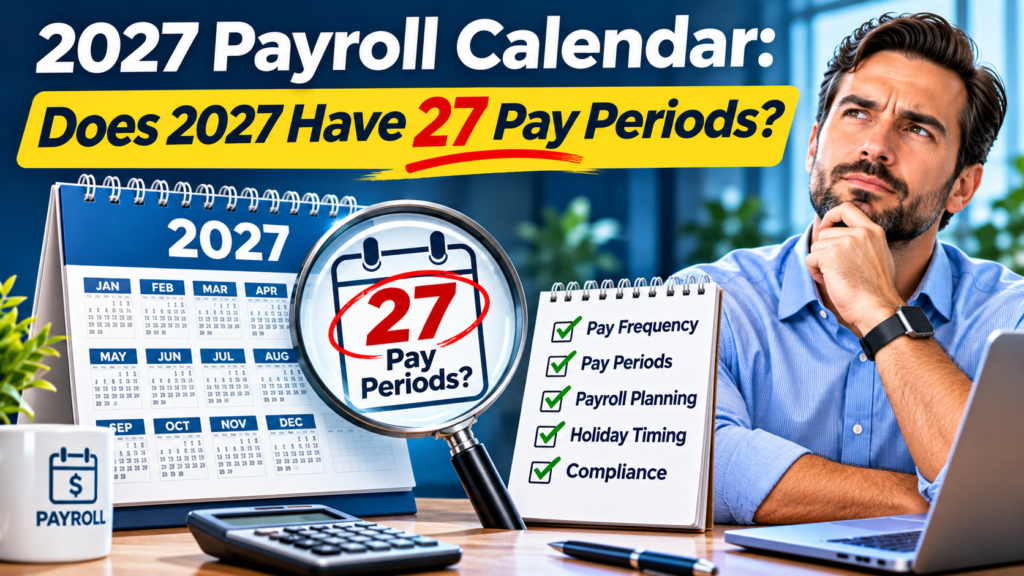
January 1, 2027 falls on a Friday, which means certain biweekly payroll schedules will produce 27 pay periods instead of the usual 26. Here is what that means for salaried paychecks, benefit deductions, and your annual budget.

January 1, 2027 falls on a Friday, and 2027 is not a leap year. That combination means a biweekly Friday payroll whose first payday lands on January 1, 2027 will generate 27 pay periods instead of the standard 26. A weekly Friday payroll will produce 53 paydays. If your 2027 payroll calendar follows either of those schedules, you need to plan now for the impact on per-paycheck salary amounts, benefit deduction totals, and cash flow.

What Is a 2027 Payroll Calendar and Why Does It Matter?

A payroll calendar is the master schedule that tells you exactly how many times employees are paid in a given plan year and on which dates those payments fall. It matters because every downstream calculation — salaried per-paycheck amounts, benefit premium splits, 401(k) contribution timing, and tax deposit deadlines — flows from that schedule.

For 2027 specifically, the calendar matters more than usual. Because January 1, 2027 is a Friday, any employer running a biweekly Friday pay cycle that starts on that date will hit 27 paydays across the year. That is not a mistake or a system glitch; it is simple calendar math. Knowing it in advance lets you make deliberate choices rather than reactive ones.

How Does the Extra Pay Period Happen?

A standard biweekly schedule produces 26 pay periods in most years (52 weeks ÷ 2). But 365 days is not evenly divisible by 14. That fractional remainder accumulates, and roughly every 11 years a Friday-payday biweekly calendar crosses into a 27th period. 2027 is one of those years for employers whose first payday falls on January 1.

A weekly Friday schedule is simpler: 2027 has 53 Fridays, so a weekly payroll has 53 pay periods. Semi-monthly payrolls (the 1st and 15th, for example) always produce exactly 24 pay periods regardless of which day January 1 falls on, so those employers are unaffected.

How to Check Your Own Schedule

To confirm whether your business is in a 27-period year, do the following:

  1. Identify your pay frequency (weekly, biweekly, semi-monthly, monthly).
  2. Find your first scheduled payday in 2027.
  3. Count forward in your pay cycle increments through December 31, 2027.
  4. If you land on a 27th payday before the year ends, you have a 27-period year.

Most payroll platforms — including Gusto, Rippling, ADP and Paychex — will display the full 2027 schedule in their calendar view. Run that report now, before January, so you have time to communicate changes to employees and adjust your general ledger.

Find out whether a PEO makes sense for your business. The PEO Calculator shows you the real cost in 60 seconds, with no call and no commitment.

Try the PEO Calculator →

Does a 27th Pay Period Change What Salaried Employees Earn?

No. A salaried employee’s annual compensation does not change because of a 27-period year. What changes is how that annual salary is divided per paycheck.

Under a standard 26-period biweekly schedule, an employee earning $78,000 per year receives $3,000 per paycheck. Under a 27-period schedule, the same annual salary divided equally produces approximately $2,888.89 per paycheck. The employee earns exactly the same amount over the year — it is simply spread across one additional payment.

That said, employers have two valid approaches:

Option 1: Divide the Annual Salary by 27

Each paycheck is slightly smaller. Employees receive their correct annual salary by year-end. This is the most mathematically straightforward approach and requires the least manual adjustment. You must communicate the change to employees in writing before the first affected payday, and in some states advance notice of a wage rate change is legally required. Check your state’s department of labor website for specific notice requirements.

Option 2: Pay the Standard 26-Period Amount and Treat the 27th as an Extra Pay

Some employers keep the per-paycheck amount the same and effectively overpay by one paycheck’s worth of salary in the 27-period year. This is simpler for employee relations but adds an unbudgeted payroll cost — often 3–4% of annual salary expense for the affected employees. For a team of 20 people earning an average of $60,000, that unplanned cost can exceed $46,000 in aggregate. Plan accordingly.

How Do Benefit Deductions Work Across 26 vs. 27 Pay Periods?

Benefit deductions are where the 27-period calendar creates the most administrative complexity, because annual premium costs are fixed but the number of times you deduct them is not.

Health Insurance Premiums

If your health plan year runs January 1 through December 31, 2027, the total employee premium contribution for the year is set by your carrier. Under a 26-period schedule, that annual amount is divided by 26. Under a 27-period schedule, you have three choices:

  • Divide by 27: Each deduction is smaller. Employees pay the correct annual amount. This is the cleanest option.
  • Skip one deduction: Take no deduction on a designated payday, typically the extra 27th period, and collect the full annual premium over the other 26. Employees see one paycheck with no benefit deduction, which can generate questions.
  • Keep 26 deductions and collect the 27th-period amount separately: This is administratively complex and generally not recommended.

Coordinate with your benefits carrier or broker before January 1, 2027. Some carriers set deduction schedules annually and will not automatically adjust for a 27-period year.

FSA and HSA Contributions

The IRS sets annual contribution limits for Health FSAs and HSAs. For 2027, the IRS has not yet published updated limits as of this writing; check IRS.gov for the official 2027 figures when they are released. Once you have the annual cap, divide by the number of pay periods you will use for deductions — not necessarily 27 if you plan to skip a period — to arrive at the per-paycheck amount.

401(k) Contributions

The IRS sets annual 401(k) elective deferral limits. For 2027, those limits have not been published yet; monitor IRS.gov/retirement-plans for the announcement, typically released in October or November of the prior year. Employees who contribute a flat dollar amount per period rather than a percentage of pay may inadvertently exceed their annual limit if the system does not cap at the IRS threshold before the 27th period. Confirm your payroll platform handles this automatically.

Which 2027 Paydays Fall on Holidays?

Holiday paydays require advance planning because banks and the Federal Reserve ACH network do not process transactions on federal holidays. If a scheduled payday falls on a federal holiday, you must either run payroll one to two business days early or push it to the next business day — but pushing it late can violate state wage payment timing laws in some jurisdictions.

Federal Holiday 2027DateDay of WeekAffects Friday Payroll
New Year’s DayJanuary 1FridayYes — first payday of year
MLK Jr. DayJanuary 18MondayNo direct conflict
Memorial DayMay 31MondayNo direct conflict
Independence DayJuly 4 (observed July 5)SundayMonday observance; check processor cutoff
Labor DaySeptember 6MondayNo direct conflict
ThanksgivingNovember 25ThursdayDay-after processing may be delayed
Christmas DayDecember 25SaturdayObserved Friday Dec 24 — direct Friday conflict

The January 1 and December 24 (Christmas Eve observed) Fridays are the two dates most likely to disrupt a Friday biweekly or weekly payroll. Confirm your payroll processor’s ACH cutoff rules and submit those runs at least one business day earlier than usual. The U.S. Department of Labor and your state wage and hour division are authoritative sources on pay timing requirements.

How Should You Budget for a 27-Period Payroll Year?

Budgeting for a 27-period year requires separating your annual salary expense from your per-period cash flow model. The annual salary expense does not change, but your monthly cash outflow will be uneven because some months will have three paydays instead of two.

Specifically, in a biweekly Friday payroll starting January 1, 2027, the months with three paydays will typically be January, April, July, and October — though this depends on where you set your fiscal quarters. Build a simple spreadsheet that maps each of the 27 paydays to a calendar month, then model the cash impact month by month. Share it with your CFO or bookkeeper before Q4 2026 planning is finalized.

For payroll tax deposits, the IRS requires employers to follow a monthly or semi-weekly deposit schedule based on a lookback period. A 27-period year does not change the deposit schedule rules, but it does mean one additional pay run triggers a deposit obligation. Review your lookback period classification at IRS.gov.

How a PEO Simplifies a Complex Payroll Year

A Professional Employer Organization (PEO) is a co-employment arrangement in which the PEO serves as the employer of record for payroll and benefits purposes. For a 27-period year, PEOs handle the schedule math automatically, adjust benefit deduction splits across the correct number of periods, manage holiday payday shifts, and ensure tax deposit timing stays compliant — all without you building a custom spreadsheet.

According to the National Association of Professional Employer Organizations (NAPEO), businesses that use PEOs grow 7–9% faster than comparable businesses that do not, and they have 23–32% lower employee turnover. In our analysis of 40+ vetted PEOs, businesses that move payroll and benefits administration to a PEO typically save 20–40% on operation and benefit costs — in part because the PEO’s pooled buying power reduces per-employee benefit premiums.

A 27-period year is also a natural prompt to evaluate whether your current payroll setup is scaling with your business. If your team has grown to 10 or more employees, the administrative lift of managing a non-standard payroll calendar, benefits reconciliation, and compliance deadlines is worth quantifying. See how leading options compare at our best PEO for small business guide, or check the Gusto vs. Justworks comparison if you are evaluating platform-based options alongside full-service PEOs.

If you want to understand what benefit costs look like for companies your size and industry, the Benefits Benchmark gives you a data-driven baseline before you start any vendor conversation.

Frequently Asked Questions

Does every company have 27 pay periods in 2027?

No. Only employers running a biweekly Friday payroll whose first payday falls on January 1, 2027 will have 27 pay periods. Semi-monthly payrolls always have 24 pay periods, and monthly payrolls always have 12. Weekly payrolls in 2027 will have 53 paydays because 2027 has 53 Fridays.

Do salaried employees get paid more in a 27-period year?

Not necessarily. If you divide annual salary by 27, each paycheck is slightly smaller and employees receive the same annual total. If you keep the per-paycheck amount the same as in a 26-period year, employees receive one additional paycheck’s worth of salary, which increases your payroll expense for that year.

How do I handle health insurance deductions in a 27-period year?

The most straightforward approach is to divide the employee’s annual premium contribution by 27, producing a slightly smaller per-paycheck deduction. Alternatively, you can skip a deduction on one designated payday and collect the full annual premium over 26 periods. Coordinate with your carrier or broker before January 1, 2027, and communicate any change to employees in advance.

What happens if my payday falls on a federal holiday in 2027?

When a scheduled payday falls on a federal holiday, ACH bank transfers cannot be processed on that date. You must either fund payroll one to two business days early or, in some states, risk a late-payment violation if you push it past the holiday. The two highest-risk Fridays in 2027 are January 1 (New Year’s Day) and December 24 (Christmas Eve observed).

Can a PEO manage the complexity of a 27-period payroll year for my business?

Yes. A PEO handles pay period math, benefit deduction adjustments, holiday payday shifts, and tax deposit compliance as part of its standard service. Based on our experience matching hundreds of businesses across 40+ vetted PEOs, employers who delegate payroll administration to a PEO report significantly fewer compliance errors during non-standard calendar years like 2027.

Get a Matched PEO Recommendation for 2027

A 27-period payroll year is a smart time to evaluate whether your HR and payroll infrastructure is built for where your business is going. Schedule a no-pressure conversation and we will match you from 40+ vetted PEOs based on your size, industry, and priorities.

Schedule a Consultation →

Prefer to compare on your own timeline first. Run the Benefits Benchmark for your industry and we will email you a breakdown of what companies your size are paying for HR, benefits and workers comp.

Run the Benefits Benchmark →

”
}

The Memorial Hermann health plan closing affects commercial employer groups across Houston and southeast Texas. Memorial Hermann is winding down three products — its HMO, PPO, and self-funded administration platform — and every employer group will lose coverage at its next renewal date through 2027. If your company relies on a Memorial Hermann commercial plan today, you have a defined deadline and a clear set of steps to protect your employees.

This post covers exactly what is ending, the timeline that applies to your group, what to verify before you switch carriers, and the replacement options available to Houston-area employers with five to one hundred employees.

What Is the Memorial Hermann Health Plan Closing?

Memorial Hermann is exiting the commercial employer health insurance market entirely, discontinuing its HMO, PPO, and self-funded administration products. Three entities are involved in the wind-down: Memorial Hermann Commercial Health Plan (the HMO), Memorial Hermann Health Insurance Company (the PPO), and Memorial Hermann Health Solutions (the self-funded administration platform). According to the Memorial Hermann employer Program Closing page, groups renewing before December 1, 2026 may elect one final plan year, and each group’s coverage ends with that plan year. No new groups are being written.

This is not a merger or an acquisition. The commercial book of business is simply closing. That means your current network, your negotiated rates, and your plan design all go away at renewal. There is no automatic transition to another carrier.

Which Employers Are Affected?

Any employer in Texas currently enrolled in a Memorial Hermann commercial group health plan is affected. That includes fully insured HMO and PPO groups as well as self-funded groups administered through Memorial Hermann Health Solutions. The wind-down is specific to commercial employer plans; it does not affect the Memorial Hermann health system’s hospital and clinic operations, which continue as normal.

What Is the Timeline?

The timeline is renewal-driven. Groups with a renewal date before December 1, 2026 may take one additional plan year, meaning their last day of coverage could fall as late as November 30, 2027. Groups renewing on or after December 1, 2026 should expect coverage to end at that renewal. Confirm your specific end date with your broker or directly with Memorial Hermann’s employer services team, because the cutoff is tied to your group’s anniversary date, not a single industrywide termination date.

Run the numbers on better benefits for your team. The PEO Calculator shows what companies your size are paying.

Try the PEO Calculator →

How Does Network Continuity Work When a Health Plan Closes?

Network continuity means ensuring your employees can keep seeing the same doctors, specialists, and facilities after switching carriers. When a commercial plan closes, that obligation does not transfer automatically to a new carrier — your team needs to verify in-network status under whatever replacement plan you choose.

Steps to Protect Employee Care

Start by collecting a list of the providers your highest-utilization employees currently see, including primary care physicians, specialists, and any ongoing therapists or behavioral health providers. Then run each provider through the network directories of your shortlisted replacement carriers before you sign anything. The Texas Department of Insurance maintains guidance on continuity of care rights during plan transitions, which may apply during the gap between termination and new coverage effective date.

For employees in active treatment — mid-chemotherapy, post-surgical recovery, or high-risk pregnancy — continuity of care is a legal and HR priority. Most Texas-regulated carriers are required to honor continuity of care for a defined transition period under state law. Confirm the specific terms with each carrier you are evaluating.

Memorial Hermann Hospitals and Clinics After the Plan Closes

It is worth repeating: the Memorial Hermann health system — its hospitals, emergency rooms, and outpatient clinics — is not closing. What is closing is the insurance entity that administered employer group coverage. Many replacement carriers in the Houston market already include Memorial Hermann facilities in their networks. Verifying that the system remains in-network under your replacement plan is one of the most important steps a Houston employer can take right now.

What Are the Replacement Options for Houston Employers?

Houston-area employers in the five-to-one-hundred-employee range have four primary paths: buying a fully insured group plan directly from a carrier, moving to a level-funded arrangement, joining a Multiple Employer Welfare Arrangement (MEWA), or working through a Professional Employer Organization (PEO) that provides group health benefits as part of a co-employment model.

OptionBest ForKey AdvantageKey Consideration
Fully insured carrier (HMO/PPO)Groups wanting predictable monthly premiumsSimple to administer; fixed costRates reset at every renewal
Level-funded planHealthier groups, 10–100 employeesPotential refund if claims run lowRequires underwriting; stop-loss caps risk
MEWA / association planIndustry associations or trade groupsGroup buying power for small employersEligibility tied to association membership
PEO co-employment model5–100 employees seeking Fortune-500-level benefitsLarge-group rates; HR and payroll bundledCo-employment relationship; PEO selects carrier

How Does a PEO Work as a Replacement Option?

A Professional Employer Organization enters a co-employment relationship with your business, putting your employees on a large shared employer group for benefits purposes. Because PEOs aggregate employees across many client companies, they negotiate health insurance as a large employer — which typically means richer plan designs and more stable rates than a small group can access independently. According to NAPEO, PEO clients grow 7–9% faster than comparable non-PEO businesses, and employee turnover is 10–14% lower. Based on our analysis of 40+ vetted PEOs, businesses that move to a PEO model often reduce operation and benefit costs by 20–40%.

The tradeoff is that the PEO selects the health carrier, so you give up some control over plan design. For many small and mid-size employers, the access to large-group networks — which in Houston often include Memorial Hermann facilities — more than offsets that limitation. You can explore how different PEOs compare on benefits and pricing at our guide to the best PEOs for small business or use the Benefits Benchmark tool to see what companies your size are paying in your industry.

Carriers Active in the Houston Market for 2027

Several fully insured and level-funded carriers actively write small and mid-size group business in the Houston metro area, including Blue Cross Blue Shield of Texas, Aetna, UnitedHealthcare, Cigna, and Oscar Health. Network breadth varies by plan tier, so a plan that lists Memorial Hermann in its directory at a broad tier is not the same as one that lists it only in a premium or buy-up tier. Request network tiering detail — not just a provider directory — when you shop.

The IRS HSA contribution limits, out-of-pocket maximums, and other cost-sharing figures that govern plan design for 2027 are set by IRS guidance issued in 2026. Confirm current figures at IRS.gov before finalizing plan selections. ACA employer shared responsibility thresholds for 2027 follow SSA cost-of-living adjustment announcements; check SSA.gov for updated figures once published.

How to Plan the Switch by Your Renewal Date

Planning the switch means working backward from your coverage end date to build a decision timeline with enough room for underwriting, enrollment, and employee communication. Rushing this process is the primary way employers end up with a gap in coverage or a plan their employees do not understand.

A Practical Transition Checklist

Start ninety days before your Memorial Hermann end date. Confirm your exact termination date in writing. Collect provider lists from your top benefits users. Issue a request for proposals to at least three alternatives — including at least one PEO quote if you have not evaluated that model before. Narrow to two finalists, verify network status for key providers, and confirm continuity of care terms for employees in active treatment. Finalize your decision sixty days out, complete enrollment, and issue employee communications no later than thirty days before the new effective date.

If your renewal falls in the first quarter of 2027, that means your RFP process should be underway now. Comparing multiple options side by side is the most effective way to avoid overpaying — see how leading platforms compare and review the Insperity cost comparison if you are evaluating larger national PEOs.

NAPEO provides additional resources on the PEO co-employment model at NAPEO.org. The Department of Labor’s Employee Benefits Security Administration offers guidance on group health plan rights and continuation coverage at DOL.gov/agencies/ebsa.

How PEO Marketplace Helps Houston Employers Through This Transition

PEO Marketplace is a licensed insurance agency that matches employers with vetted benefit and HR solutions. Our network includes 40+ vetted PEOs, and our matching process is built around your industry, headcount, location, and benefit priorities — not a commission incentive to push one provider. The problem with the employer benefits buying process is that most business owners see only one or two options at a time, often from a single agent representing a single carrier. Seeing several options side by side, with apples-to-apples cost and network data, produces better decisions.

Use the Find Your PEO tool to begin a structured comparison, or book a call below to walk through your Memorial Hermann transition with an advisor who works across multiple carriers and PEO platforms.

Your Memorial Hermann coverage has a known end date. Start your replacement search now.

An advisor from PEO Marketplace will map out your options across carriers and PEOs with no obligation and no sales pressure — just a clear comparison.

Schedule a Transition Planning Call →

Prefer to compare on your own timeline first. Run the Benefits Benchmark for your industry and we will email you a breakdown of what companies your size are paying for HR, benefits and workers comp.

Run the Benefits Benchmark →

Frequently Asked Questions

When exactly does Memorial Hermann health plan coverage end for my group?

Your coverage ends at the conclusion of your current plan year. Groups renewing before December 1, 2026 may elect one final plan year, so the latest possible end date for most affected groups is in late 2027. Confirm your specific termination date in writing with Memorial Hermann’s employer services team, because the date is tied to your group’s anniversary date.

Will my employees still be able to use Memorial Hermann hospitals after the plan closes?

Yes. The Memorial Hermann health system — its hospitals, emergency rooms, and outpatient clinics — is not closing. Only the commercial insurance entities are winding down. Employees can continue using Memorial Hermann facilities as long as those facilities are in-network under your new replacement plan, so verifying network status before you switch carriers is a critical step.

Is there a COBRA continuation option when the plan terminates?

Federal COBRA rules generally apply when group health plan coverage ends, but COBRA continuation is tied to the original plan, which will no longer exist after termination. Employees will need to enroll in a new group plan through your replacement carrier or explore individual marketplace coverage. The Department of Labor’s guidance on group health continuation rights is available at DOL.gov/agencies/ebsa.

How much does it cost to switch to a new carrier or PEO?

Direct carrier replacement costs vary by plan design, employee demographics, and the carrier’s small-group rating methodology; 2027 benchmark figures have not been universally published yet, so request quotes specific to your group. Employers who move to a PEO co-employment model often see operation and benefit costs reduce by 20–40%, based on our analysis of 40+ vetted PEOs, primarily because PEOs access large-group underwriting that small employers cannot reach independently.

How far in advance should Houston employers start shopping for a replacement plan?

Start the replacement process at least ninety days before your Memorial Hermann coverage end date. That window allows time for underwriting, network verification, enrollment, and employee communication without creating a gap in coverage. Employers with complex workforces or employees in active treatment may need to start earlier to address continuity of care requirements.

When your headcount crosses 50 full-time equivalent employees, the IRS classifies you as an Applicable Large Employer (ALE) under the Affordable Care Act — and the compliance costs that come with that label catch most growing businesses completely off guard. The affordability requirements, variable-hour tracking, and IRS reporting obligations represent a significant hidden cost that does not show up in a simple hiring plan. Understanding ACA compliance costs before you cross that threshold is the difference between a smooth growth year and a five-figure penalty bill.

Why 50 Employees Is a Legal Turning Point

The 50-employee threshold under the ACA is not a suggestion — it is a hard federal trigger. Under IRS Code Section 4980H, once you average 50 or more full-time equivalent (FTE) employees over the prior calendar year, you become an Applicable Large Employer. That status brings a set of mandatory obligations that simply do not exist for smaller employers.

Here is what changes overnight:

  • You must offer health coverage to at least 95% of your full-time employees (those working 30+ hours per week) and their dependents up to age 26.
  • That coverage must meet affordability standards — in 2026, an employee’s share of the lowest-cost single plan cannot exceed 9.02% of their household income (using IRS safe harbors).
  • Coverage must meet minimum value — the plan must cover at least 60% of total allowed costs.
  • You must file IRS Forms 1094-C and 1095-C annually, reporting health coverage details for every full-time employee.

Most business owners at 42 or 47 employees think they have time. The reality: the ACA counts your prior-year average, meaning you could already be an ALE right now without realizing it. According to the IRS ALE guidance, part-time and seasonal workers are converted into FTE equivalents and counted — which means a 38-person company with heavy part-time staff could already be above 50 FTEs on paper.

Worried about staying compliant as you grow? Our free PEO calculator shows what it costs to offload payroll, compliance, and HR to a PEO — 60 seconds, no call needed.

Try the Free Calculator →

Breaking Down the Real ACA Compliance Costs

ACA compliance costs are not just about buying health insurance. They are about the operational infrastructure you need to stay legally protected. Here is where the money actually goes.

1. Variable-Hour Employee Tracking

The ACA requires you to track and measure hours for every variable-hour, part-time, and seasonal employee to determine whether they qualify as full-time. This is done through a formal measurement period — either a standard or initial measurement period lasting 3 to 12 months — followed by an administrative period and a stability period during which you must offer (or not offer) coverage based on what you measured.

If your payroll system is not built for this, you are looking at manual spreadsheet tracking, which introduces error risk — and errors lead to penalties. Upgrading to an ACA-compliant HR and payroll system typically costs $3,000 to $8,000 per year for a company your size, depending on the platform.

2. Affordability Calculation and Plan Design

The 2026 affordability threshold is 9.02% of an employee’s W-2 wages (one of three IRS safe harbors). You need someone — an HR professional or benefits advisor — to calculate the maximum employee contribution for every plan you offer, then verify your plans qualify as minimum value. Get this wrong and the IRS can assess a penalty of $4,460 per employee per year (2026 indexed amount) for plans that fail affordability — even if you offered coverage.

3. IRS Reporting: Forms 1094-C and 1095-C

Every ALE must file Form 1094-C (the transmittal) and a Form 1095-C for each full-time employee by the March 31 deadline for electronic filers. This is not a simple form — each 1095-C requires you to accurately code Line 14 (offer of coverage), Line 15 (employee required contribution), and Line 16 (safe harbor codes) for every month of the year.

Outsourcing this reporting to a CPA or benefits firm typically runs $2,000 to $6,000 annually for a 50-employee company. Doing it in-house requires significant staff time — industry estimates put it at 80 to 120 hours per year when you include data gathering, coding, employee distribution, and IRS filing.

4. ACA Penalty Exposure

The IRS enforces ACA compliance through Employer Shared Responsibility Payments (ESRP). There are two categories:

  • 4980H(a) Penalty — “A” Penalty: Triggered if you fail to offer coverage to 95% of full-time employees and even one employee gets a premium tax credit on the marketplace. The 2026 penalty is approximately $2,900 per full-time employee (minus the first 30), annually.
  • 4980H(b) Penalty — “B” Penalty: Triggered if you offer coverage but it fails affordability or minimum value and an employee gets a marketplace subsidy. The 2026 penalty is approximately $4,460 per affected employee annually.

For a 52-employee company, an “A” penalty would run roughly $63,800 per year. That is not a theoretical number — the IRS is actively issuing Letter 226-J notices to employers who undercounted their FTEs or missed filing deadlines. According to the Department of Labor, ACA enforcement activity has increased significantly heading into 2026.

DIY vs. PEO: What ACA Compliance Actually Costs You

Let us put real numbers on the table. Based on our analysis of 100+ PEO providers and the companies we have helped match, here is a realistic cost comparison for a 50-employee business managing ACA compliance.

Compliance TaskDIY Annual CostThrough a PEO
ACA-compliant payroll/HR system$3,000–$8,000Included
Variable-hour tracking setup and maintenance$2,000–$5,000 (staff time)Included
1094-C / 1095-C filing (outsourced or internal)$2,000–$6,000Included
Benefits advisor / broker fees$3,000–$10,000Included
HR staff time (compliance research, audits)$5,000–$15,000Included
Penalty risk exposure (if errors occur)$4,460–$63,800+PEO assumes liability
Total Estimated Annual Cost$15,000–$44,000+$12,000–$24,000 (avg PEO fee)

The cost of a PEO often comes out close to or below what you would spend managing compliance in-house — without the liability exposure. According to NAPEO research, businesses that use a PEO grow 7 to 9 percent faster and have 10 to 14 percent lower employee turnover than those that do not. The compliance infrastructure is one big reason why.

What Is a PEO and How Does It Handle ACA Compliance?

A Professional Employer Organization (PEO) is a company that co-employs your workforce alongside you, taking on the administrative and legal responsibilities of being an employer — including ACA compliance. You keep full control of your day-to-day operations and who you hire. The PEO handles payroll, benefits, HR compliance, tax filings, and reporting.

When it comes to ACA compliance costs specifically, a PEO:

  • Tracks variable-hour employees through their platform automatically
  • Calculates affordability for your workforce and flags issues before they become penalties
  • Files 1094-C and 1095-C under their EIN in many arrangements, absorbing the filing obligation
  • Provides access to large-group health insurance rates that can be 10 to 30 percent cheaper than what a 50-person company can negotiate directly
  • Responds to IRS Letter 226-J notices on your behalf if they arise

If you are not familiar with PEOs yet, our guide to the best PEOs for small businesses is a good starting point. You can also see how specific providers handle these compliance layers in our comparison of Gusto and Justworks or our Insperity cost breakdown.

When Should You Start Preparing?

The answer is before you hit 50 employees — ideally when you are at 40 to 45. Here is why timing matters so much:

  • The ACA looks at your prior calendar year average, so if you cross 50 FTEs this year, your obligations start January 1 of next year — but the measurement period that determines who gets coverage offers starts now.
  • Setting up a compliant tracking system after the fact is expensive and creates retroactive risk.
  • Health plan design needs to happen during open enrollment, which means you need your affordability calculations done months in advance.
  • If you plan to use a PEO, onboarding takes 4 to 6 weeks — you want that done before the compliance clock starts ticking.

In our experience matching hundreds of businesses, the companies that call us at 42 employees have a smooth transition. The ones who call us at 52 employees — already in ALE status with no systems in place — are scrambling. Use our free PEO matching service to get ahead of it.

Bottom Line: The 50-Employee Threshold Is a Business Decision, Not Just an HR Problem

Crossing 50 employees is an exciting milestone. It means your business is growing, your team is expanding, and you are building something real. But the ACA compliance costs that come with that milestone are significant, concrete, and enforceable. The good news is that the infrastructure to handle them does not have to be built from scratch inside your company. A PEO can absorb the complexity, reduce your liability, and often lower your total cost at the same time.

You have built too much to let a compliance gap become a six-figure problem.

Ready to Stop Worrying About ACA Compliance?

Book a free 20-minute consultation with a PEO Marketplace advisor. We will review your headcount, your current HR setup, and match you with the right PEO for your industry and size — at no cost to you.

Book Your Free Consultation →

Not ready to book a call? Get a free Benefits Benchmark Report for your industry — we will email you a breakdown of what companies your size are paying for HR, benefits, and workers comp so you can compare on your own timeline.

Get My Free Benchmark Report →

Frequently Asked Questions

How does the ACA count employees to determine if I am an Applicable Large Employer?

The ACA counts full-time employees (averaging 30+ hours per week) plus full-time equivalents, which are calculated by adding all part-time hours in a month and dividing by 120. If your total averaged 50 or more FTEs across the prior calendar year, you are an ALE subject to ACA employer mandate requirements for the current year.

What is the ACA affordability threshold for 2026?

For 2026, a health plan is considered affordable under ACA rules if the employee’s required contribution for the lowest-cost single-coverage plan does not exceed 9.02% of their household income. Employers typically use one of three IRS safe harbors — W-2 wages, rate of pay, or federal poverty line — to establish affordability without knowing each employee’s actual household income.

What happens if I miss filing Forms 1094-C and 1095-C?

Failure to file or furnish correct 1095-C forms to employees can result in penalties of $310 per return in 2026, with a maximum annual penalty of $3,783,000 for large filers. Intentional disregard of the filing requirement raises the per-return penalty significantly higher, with no annual cap.

Can a PEO actually take on my ACA compliance liability?

Yes — in a co-employment arrangement, many PEOs file ACA reporting under their own EIN and assume responsibility for the accuracy of that filing, which shifts significant compliance liability away from you as the client employer. However, the specifics vary by PEO, so it is important to review the contract terms carefully, which is something PEO Marketplace helps clients do during the matching process.

Is it cheaper to manage ACA compliance in-house or through a PEO?

Based on our analysis of 100+ PEO providers and the businesses we match, most 40-to-55-employee companies spend $15,000 to $44,000 per year managing ACA compliance in-house when you account for software, staff time, outside advisors, and penalty risk — while a PEO typically costs $12,000 to $24,000 annually and includes compliance as part of the service. Use our free PEO cost calculator to run the numbers for your specific situation.

Construction companies paying $7–$12 per $100 of payroll for workers comp can realistically cut that number by 20–30% without reducing coverage — by using a combination of experience mod management, classification audits, safety program credits, and PEO master policy pooling. Based on our analysis of 100+ PEO providers, the single biggest lever most small and mid-size contractors overlook is joining a PEO master policy, which pools your 20-person crew alongside tens of thousands of workers for dramatically lower blended rates.

Why Construction Workers Comp Costs Are So High

Workers compensation in construction is expensive for a straightforward reason: the work is physically dangerous. Falls, equipment injuries, overexertion, and struck-by incidents make construction one of the highest-risk industries in the country. According to the Bureau of Labor Statistics, construction accounts for roughly 20% of all private-sector fatal workplace injuries despite employing less than 5% of the private-sector workforce.

Insurers price that risk into your premium. The base rate for common construction classifications — framing crews, roofing, concrete work, electrical — typically runs $7–$15 per $100 of payroll depending on the class code and your state. Before you factor in your experience modification rate (EMR), you’re already paying multiples of what a desk-job employer pays. Add an EMR above 1.0 and your premiums compound fast.

The good news: most of what drives those costs is manageable. Here’s exactly how to attack each lever.

Overpaying for workers comp is more common than most businesses think. Our free PEO calculator breaks down what you would actually pay through a PEO — try it in 60 seconds.

Try the Free Calculator →

Lever 1: Experience Mod Management

Your experience modification rate (EMR or mod) is a multiplier applied to your base workers comp premium. An EMR of 1.0 is average. An EMR of 0.85 means you pay 15% less than average. An EMR of 1.25 means you pay 25% more — and it compounds every renewal until your loss history improves.

How the EMR Is Calculated

Your mod is calculated by your state’s rating bureau (NCCI in most states) using three years of claims data, excluding the most recent policy year. It compares your actual losses to what would be expected for a company your size in your classification. Frequent small claims hurt your mod almost as much as large ones — which is why some contractors make the mistake of filing claims for minor incidents they could handle out of pocket.

How to Drive Your EMR Down

  • Dispute inaccurate claims data. Errors in your unit statistical report — closed claims showing as open, incorrect reserves, misclassified incidents — can artificially inflate your mod. Request your loss runs annually and review them line by line.
  • Implement a return-to-work program. Modified duty reduces the total incurred cost of a claim, which directly lowers your mod. Even light administrative tasks count.
  • Manage reserves aggressively. Work with your insurer to close claims quickly and reduce open reserves. Every dollar of reserve reduction can lower your future mod.
  • Track your prospective mod. Most contractors wait until renewal to see their new EMR. You can calculate it earlier and model the impact of closing specific claims before the snapshot date.

A construction company with an EMR of 1.30 that systematically drops it to 0.95 over three policy years is effectively cutting their workers comp premium by more than 25% on base rates alone — before touching anything else.

Lever 2: Workers Comp Classification Audits

Misclassification is one of the most expensive and most common problems in construction workers comp — and it almost always works against the employer. Workers assigned to higher-risk class codes than their actual duties warrant are generating inflated premiums that you’re paying right now.

Common Construction Classification Errors

The National Council on Compensation Insurance (NCCI) maintains hundreds of class codes. In construction, common errors include:

  • Office staff or project managers coded under field crew classifications
  • Finish carpenters coded under framing or rough carpentry codes (higher rate)
  • Drivers coded under general laborer classifications
  • Workers doing multiple roles with 100% of their payroll allocated to the highest-risk code

Under NCCI rules, when a worker performs duties that span multiple classifications, payroll should be split by the time spent in each role — provided you keep contemporaneous records. Most small contractors don’t keep those records, so auditors assign all payroll to the highest applicable code by default.

What a Classification Audit Looks Like

A classification audit is a systematic review of every worker’s actual job duties compared to their assigned code. You’ll want a workers comp specialist or PEO with construction experience to run this — not a generalist. In our experience matching hundreds of construction businesses, a thorough classification review typically uncovers 5–15% in premium savings before any other changes are made.

Lever 3: Safety Program Credits

Most states allow insurers to apply scheduled credits — discounts applied at the underwriter’s discretion — for documented safety programs. These credits can range from 5% to 25% depending on the state and insurer, and they are entirely separate from your EMR. You don’t have to earn them by having a great loss history; you earn them by proving you have systems in place to prevent losses.

What Qualifies for Safety Credits

  • Written safety program with documented training records
  • OSHA 10 or OSHA 30 certifications for supervisory staff
  • Toolbox talks documented weekly
  • Drug-free workplace program
  • Designated safety officer or third-party safety consultant
  • Pre-hire physical or post-offer medical exams

According to NAPEO, PEO clients experience 12% fewer workplace injuries than non-PEO employers of similar size — in part because PEOs bring structured safety programs that small contractors wouldn’t otherwise have the HR infrastructure to implement.

If your current carrier hasn’t offered you a scheduled credit in the last two years, ask for one — or find an insurer who will. Safety credits are a negotiable underwriting tool, not an automatic benefit.

Lever 4: PEO Master Policy Pooling — The Biggest Game-Changer for Small Crews

This is where construction companies with 10–100 employees have the biggest opportunity, and where most owners have never looked. A PEO master workers comp policy pools your workforce into a much larger insured group — in some cases alongside 50,000 or more workers — which fundamentally changes how your risk is priced.

How PEO Master Policy Pooling Works

When you partner with a PEO, your employees become co-employees of the PEO for HR and insurance purposes. The PEO carries a master workers comp policy that covers all of its client companies. Because the insured population is massive and diversified, the PEO negotiates base rates that individual small contractors simply cannot access on their own.

Think of it this way: an insurance company sees your 20-person framing crew as a volatile, small risk. One bad year with a serious injury could double their loss ratio on your account. They price for that uncertainty. When your 20 workers are part of a pool of 50,000 construction, healthcare, and professional services workers, the volatility smooths out. The insurer prices for the pool — not for your worst-case year.

What This Means for Your Premium

In practical terms, construction contractors working through a PEO master policy commonly see base rate reductions of 20–40% compared to their standalone policy. This isn’t a reduction in coverage — you still carry the same statutory limits, the same employer liability, the same certificate of insurance for your GC requirements. The coverage is identical. The cost structure is different because your risk is priced differently.

Not every PEO offers construction coverage or accepts high-mod contractors, so the matching process matters. At PEO Marketplace, we specifically vet PEOs for construction industry experience and master policy availability — you can explore your options through our PEO matching service or check our top-rated PEOs for small businesses for construction-friendly options.

Cost DriverTypical Savings PotentialTimeline to RealizeDIY or Needs PEO?
EMR Improvement10–30%2–3 yearsDIY with guidance
Classification Audit5–15%Next renewalSpecialist recommended
Safety Program Credits5–25%Next renewalDIY with documentation
PEO Master Policy20–40%Immediate at enrollmentRequires PEO partnership

Is a PEO Right for Your Construction Company?

A PEO isn’t a fit for every contractor, but for companies with 10–150 employees paying high workers comp rates, the math is often compelling. Beyond workers comp, PEOs handle payroll, HR compliance, and benefits administration — which means you’re not just buying cheaper insurance, you’re offloading a significant administrative burden so you can stay focused on project work.

According to NAPEO research, businesses that use PEOs grow 7–9% faster and have 10–14% lower employee turnover than non-PEO businesses. For a construction company trying to hold onto skilled labor in a tight market, that retention benefit alone can justify the partnership.

High-mod contractors (EMR above 1.20) may face restrictions with some PEOs, but others specialize in exactly this situation. Our free PEO cost calculator can give you a ballpark estimate of what you’d pay through a PEO versus your current standalone policy, and our benefits benchmark tool shows you how your total comp package compares to others in your industry.

For a deeper comparison of specific providers, see how larger national PEOs stack up in our Insperity cost comparison.

The IRS formally recognizes certified PEOs (CPEOs) for tax liability purposes, which adds another layer of protection for construction employers handling complex multi-state payroll.

How to Get Started Cutting Your Construction Workers Comp Costs

Here’s a practical action plan for a construction company owner ready to move:

  1. Pull your current loss runs (3–5 years) and your current EMR from your carrier or broker. Know your baseline.
  2. Request your unit statistical report from NCCI and check for errors in how your claims are being reported.
  3. Audit your class codes. Have a specialist review every employee’s assigned classification against their actual duties and payroll allocation.
  4. Document your safety program. Even if you’re already doing toolbox talks and OSHA training, get it in writing and request a scheduled credit from your carrier.
  5. Get a PEO comparison. Ask a PEO marketplace consultant to run the numbers on master policy rates for your specific classifications and crew size.

Most construction companies can implement all four levers simultaneously. You don’t have to choose between fixing your EMR and joining a PEO — in fact, PEOs with strong safety programs actively help you improve your mod over time, compounding the savings year after year.

Ready to See What You’d Actually Pay?

Book a free 20-minute call with a PEO Marketplace advisor. We’ll review your current workers comp costs, run PEO comparisons for construction-specific providers, and give you a clear picture of what’s possible — no obligation.

Book My Free Consultation →

Frequently Asked Questions

Can a construction company with a high EMR still join a PEO master policy?

Some PEOs do accept contractors with elevated experience mod rates, though the options narrow as EMR climbs above 1.30. In our experience matching construction businesses, specialty PEOs with deep construction industry experience are far more likely to work with high-mod contractors than generalist providers. The key is working with a broker who knows which PEOs have appetite for your classification and loss history.

Does joining a PEO affect my ability to get a certificate of insurance for GC requirements?

No — a PEO issues certificates of insurance naming your company as the insured entity, which satisfies general contractor and project owner COI requirements. The coverage is the same statutory workers comp coverage your subs and GCs require; it simply runs through the PEO’s master policy. Most PEOs with construction experience handle COI requests routinely and quickly.

How long does it take to see savings after switching to a PEO?

The workers comp rate reduction through a PEO master policy is immediate — it takes effect when your enrollment begins, not at your next standalone policy renewal. EMR improvements take longer because they reflect rolling three-year claims history, but the base rate savings through pooling start on day one.

What’s the difference between a PEO and just using a staffing company for my crew?

A staffing company places workers at your jobsite but retains full employer control — you have limited ability to direct HR policies, safety programs, or benefits. A PEO co-employs your existing workers in a shared model where you retain full operational and supervisory control, while the PEO handles payroll, compliance, benefits, and workers comp. PEO co-employment is specifically designed to give small contractors access to Fortune 500-level HR infrastructure without giving up control of their crews.

Are the savings real, or do PEOs add fees that eat up the workers comp discount?

PEO fees are real and should be factored into your total cost comparison — a reputable PEO will be transparent about their per-employee-per-month or percentage-of-payroll fee structure. In our analysis, construction companies with 15 or more employees typically see net savings even after PEO fees, because the workers comp reduction and payroll processing savings outweigh the management cost. Use our free PEO calculator to model the net number for your specific headcount and payroll.

Not ready to book a call? Get a free Benefits Benchmark Report for your industry — we will email you a breakdown of what companies your size are paying for HR, benefits, and workers comp so you can compare on your own timeline.

Get My Free Benchmark Report →

A 30-person company can absolutely offer the same caliber of health insurance, retirement plans, and ancillary benefits as a 5,000-employee corporation — the mechanism is called group pooling, and it levels the playing field entirely. The traditional benefits gap between small and large employers is real, but it is not permanent. With the right structure in place, your team of 30 can access the same carrier networks, the same plan tiers, and the same employer contribution rates that Fortune 500 HR departments have been quietly leveraging for decades.

Why Small Company Benefits Cost More (And Cover Less)

The core problem is actuarial math. Insurance carriers price group health plans based on risk, and risk is calculated across a pool of lives. The larger the pool, the more predictable the claims, and the lower the per-person premium. When you have 30 employees, your pool is tiny — one cancer diagnosis, one premature birth, or one chronic condition can send your renewal rates soaring 30% to 50% in a single year.

This is not speculation. According to the Kaiser Family Foundation 2023 Employer Health Benefits Survey, small firms (under 200 employees) pay meaningfully more per employee in premiums than large firms — and they cover a smaller share of dependent costs. The average annual premium for employer-sponsored family coverage was $23,968 in 2023. But the employer contribution percentage drops significantly at smaller firms. Large employers covered roughly 73% of family premiums; small employers averaged closer to 63%. That gap comes directly out of your employees’ paychecks.

The disparity goes beyond raw premium dollars. Small group plans also tend to offer narrower networks, higher deductibles, fewer plan options, and less favorable pharmacy formularies. When a candidate with three job offers is comparing benefits side by side, your small group plan often loses before the conversation about salary even begins.

The Hidden Cost of Small Group Insurance

Small group rates are set by state-regulated small group markets, which cap the risk pool at your headcount. Carriers also apply age-rating factors more aggressively in small groups, meaning a team with several employees in their 50s can face dramatically higher base rates than a younger team of identical size. You have almost no negotiating leverage — you are a single client representing a negligible fraction of a carrier’s book of business. Large employers, by contrast, negotiate custom plan designs, onsite clinics, and wellness credits that simply are not available to you at 30 lives.

What Your Employees Are Actually Comparing

Your team knows what benefits look like elsewhere. Per BLS data from 2023, 96% of workers at large private firms have access to medical care benefits, compared to 53% at small firms. Even among small firms that do offer coverage, the plan quality gap is significant. Employees talk to former colleagues, compare LinkedIn profiles, and make decisions based on total compensation — and benefits are increasingly the deciding factor, especially for workers over 35 with families.

Wondering if a PEO could get your team better benefits for less? Run the numbers yourself — our free calculator shows you what companies your size are actually paying.

Try the Free Calculator →

How Group Pooling Eliminates the Size Disadvantage

Group pooling is the mechanism by which a Professional Employer Organization (PEO) aggregates the employees of hundreds or thousands of client companies into a single master health plan. Instead of your 30 employees forming their own tiny risk pool, they join a pool that may contain 50,000, 100,000, or even 500,000 covered lives. The carrier now prices the plan against that massive, diversified pool — and your employees get the same rates and plan design as if they worked for a company with thousands of employees.

This is not a loophole. This is precisely how the PEO industry is structured and why, according to NAPEO, businesses that use PEOs grow 7 to 9 percent faster and have 10 to 14 percent lower employee turnover than comparable businesses that do not. The benefits advantage is a primary driver of that retention edge.

What Gets Unlocked When You Join a PEO Group Plan

In our experience matching hundreds of businesses to PEO providers at PEO Marketplace, the benefits upgrade that clients experience when moving from small group to a PEO group plan typically includes several meaningful improvements across the board:

  • Lower premiums: Because the pool is large and stable, base rates are typically 10% to 30% lower than comparable small group plans in the same market.
  • Richer plan options: PEO master plans often offer multiple tiers — PPO, HMO, HDHP with HSA — giving employees genuine choice rather than a single take-it-or-leave-it option.
  • Broader networks: Large group plans negotiate directly with major carrier networks. Your employees get the same in-network access as corporate employees at large companies.
  • Stable renewal rates: Because your claims are diluted across tens of thousands of members, one bad claims year does not crater your renewal. Your rate is tied to the pool’s experience, not yours alone.
  • Ancillary benefits at scale: Dental, vision, life, disability, and even mental health benefits are bundled into the group plan at rates a standalone 30-person company could never negotiate independently.

Retirement Benefits: The Other Half of the Gap

Health insurance gets the headlines, but retirement is where the small company benefits gap quietly damages your recruiting. Large employers offer 401(k) plans with institutional investment options, lower expense ratios, and meaningful employer match structures. Small companies often either skip the 401(k) entirely or offer plans with limited fund menus and higher administrative fees that eat into employee returns.

PEOs solve this too. Most established PEOs offer access to a multiple employer plan (MEP) or pooled employer plan (PEP) 401(k), which again aggregates assets across many employers to unlock institutional pricing and fiduciary protection. Per IRS guidance on Pooled Employer Plans, the SECURE Act expanded access to these structures specifically to help small businesses compete on retirement benefits. A PEO is the most efficient delivery vehicle for that access.

The Real Competitive Advantage: What Your Benefits Package Now Says About You

There is a talent narrative embedded in every benefits package. When a candidate opens your enrollment guide and sees a choice of three health plans, a $500 wellness stipend, mental health parity coverage, a 4% 401(k) match, and employer-paid dental and vision — they do not see a 30-person company. They see an employer who takes care of people. That perception is worth more than a marginal salary bump in most cases, and it costs you significantly less to deliver when you are operating inside a PEO’s group structure.

Based on our analysis of 100+ PEO providers at PEO Marketplace, the businesses that make the biggest talent gains after switching are not necessarily the ones who were paying the least before. They are the ones who were paying market rate for mediocre small group coverage and then discovered they could pay the same or less for a genuinely competitive benefits package. The math surprises people every time.

What This Looks Like in Practice

Consider a 30-person professional services firm in Texas. Before joining a PEO, they offered a single BCBS small group PPO with a $1,800 individual deductible and covered 60% of employee-only premiums — about average for their size. After moving to a PEO group plan, they offered three plan options (including an HDHP with HSA employer seed), dropped the individual deductible on the PPO tier to $1,200, and increased employer contribution to 80% of employee premiums — all at a total monthly cost within 5% of what they had been paying before. Employee satisfaction scores on benefits jumped 40 points in the first annual survey.

That is not an outlier. That is a representative outcome. You can use our PEO cost calculator to model what a comparable shift might look like for your headcount and current spend.

How to Evaluate Your Options

Not every PEO group plan is built the same. Before you commit, you need to understand the carrier behind the master plan, the actuarial basis for the rates you are being quoted, and what your renewal exposure looks like if the overall pool has a bad claims year. You should also understand whether the PEO is quoting you on a fully-insured or self-funded master plan — the risk and flexibility profiles are different.

Our guide to the best PEOs for small businesses breaks down which providers have the strongest benefits programs for companies under 50 employees, and our Benefits Benchmark Report shows you what companies your size in your industry are actually spending on health, dental, vision, and retirement — so you have a real baseline before you start any comparison.

Benefits Dimension30-Person Company (Small Group)30-Person Company (via PEO)
Health plan options1–2 plans3–5 plans including HDHP
Employer premium contribution~63% (KFF 2023)75–85% typical
Network breadthStandard small groupLarge group negotiated network
Renewal rate volatilityHigh (claims-experience rated)Low (pool-diluted)
Dental and visionOptional add-on, limitedBundled at group rates
401(k) plan qualityLimited funds, higher feesInstitutional MEP/PEP access
Mental health coverageBasic parity, limited EAPRobust EAP + telebehavioral health

If you want to see how specific providers stack up on benefits quality and cost, our breakdowns of Insperity’s cost vs. competitors and Gusto vs. Justworks are good starting points for understanding where different PEOs land on the benefits quality spectrum.

Your Employees Deserve the Same Coverage — Full Stop

The benefits gap between small and large employers is a structural artifact of how insurance markets are organized — it is not a reflection of how much you value your team. Your employees have the same health needs, the same family obligations, and the same financial futures as employees at companies 100 times your size. They should not be penalized for working at a growing company rather than an established one.

Group pooling through a PEO is the most practical, well-tested mechanism available to close that gap today. It does not require you to be large. It requires you to make a smart structural decision about how your HR and benefits are administered. That decision, in our experience, is one of the highest-ROI moves a growing company can make — both in dollars saved and in talent retained.

The first step is understanding what you are currently spending and what you could be getting instead. Tell us about your company and we will match you with vetted PEO providers whose benefits programs fit your headcount, industry, and budget.

Ready to See What Your Team Could Be Getting?

Our advisors have matched hundreds of businesses to PEOs with benefits packages that rival the Fortune 500. The consultation is free, unbiased, and takes 30 minutes. Book a call and find out exactly what is possible for your company size and budget.

Book Your Free PEO Consultation →

Not ready to book a call? Get a free Benefits Benchmark Report for your industry — we will email you a breakdown of what companies your size are paying for HR, benefits, and workers comp so you can compare on your own timeline.

Get My Free Benchmark Report →

Frequently Asked Questions

Why do small companies pay more for health insurance than large companies?

Small companies are rated on their own claims experience, which is volatile and unpredictable with a small headcount. Large companies are rated across a massive, diversified pool of lives, which smooths out individual high-cost claims and results in lower per-member premiums. The larger the pool, the more predictable the risk — and predictability is what carriers reward with lower rates.

What is group pooling and how does it help small businesses?

Group pooling is the practice of combining employees from multiple small companies into a single large group health plan, typically administered through a PEO. By pooling hundreds of thousands of covered lives together, small businesses access large-group carrier rates, broader plan options, and more stable renewal pricing that would be impossible to negotiate on their own.

Will switching to a PEO group plan actually save my company money?

In many cases, yes — particularly for companies that currently have older workforce demographics, a history of high claims, or are renewing in a tight small group market. Based on our analysis of 100+ PEO providers, most companies see either cost neutrality or meaningful savings when moving from small group to a PEO master plan, while simultaneously improving plan quality. The free PEO calculator at PEO Marketplace lets you model your specific scenario before making any commitment.

Are PEO benefits plans available to companies with fewer than 50 employees?

Yes. Most PEOs serve companies starting at five employees, and many specialize in the 10-to-100 employee range where the benefits gap is most acute. There is no minimum headcount requirement to access PEO group health benefits, which is precisely why this model exists — to serve businesses that would otherwise be stuck in the small group market.

What happens to our benefits if we leave the PEO later?

When a company exits a PEO, they transition back to the small group market or another arrangement for health benefits. Employees typically have COBRA rights during the transition, and most businesses that exit PEOs do so by moving to a different PEO rather than returning to standalone small group plans. It is worth discussing transition terms and benefits continuity with any PEO before signing an agreement.

The average restaurant employee health insurance cost runs $7,000–$9,000 per employee per year for employer-sponsored coverage in 2026, with employers typically covering 70–80% of the premium for single coverage. But for most restaurant owners, the real problem isn’t the sticker price — it’s that standard small-group health plans were designed for office workers with fixed schedules, not hourly staff with 40% annual turnover. Here is what you are actually up against, and what your real options are.

What Does Health Insurance Actually Cost for Restaurant Employees in 2026?

According to the KFF Employer Health Benefits Survey, the average annual employer premium contribution for single coverage is $8,435 per employee, and for family coverage it rises to $16,378. Employers cover roughly 83% of single premiums and 73% of family premiums on average across all industries.

Restaurant operators, however, almost never see those average numbers. Your actual cost is shaped by three factors that are unique to food service: your workforce age mix, your geographic location, and — most critically — how many employees actually enroll.

Typical Restaurant Employer Premium Costs by Plan Type

Plan TypeAvg. Employer Cost / Employee / YearEmployee Pays (Monthly)Best For
HMO (Small Group)$6,800–$8,200$120–$180Single-location, stable staff
PPO (Small Group)$8,500–$11,000$160–$250Higher earners, managers
HDHP + HSA$5,400–$7,200$80–$140Younger, healthier workforce
Level-Funded Plan$5,000–$7,500$90–$16015+ enrollees, low claims history
ICHRA (Individual Coverage HRA)$3,600–$6,000 (employer sets)Varies by marketplace planPart-time, variable-hour staff

Wondering if a PEO could get your team better benefits for less? Run the numbers yourself — our free calculator shows you what companies your size are actually paying.

Try the Free Calculator →

Why Restaurant Owners Struggle More Than Other Employers

The standard small-group insurance market was not built with your workforce in mind. Three structural problems make health benefits uniquely difficult for restaurants.

1. Participation Requirements Kill the Plan Before It Starts

Most small-group carriers require 70% of eligible employees to enroll before they will issue a policy. In a restaurant where many workers are young, healthy, and would rather keep the $120/month in their paycheck, hitting 70% participation is genuinely hard. If you miss the threshold, the carrier either declines to write the group or rates you as if everyone on the team is a high-cost claimant. Either way, you lose.

The Department of Labor sets minimum participation rules that carriers must follow under ACA small group market reforms, but carriers can and do apply stricter thresholds in many states.

2. Turnover Destroys Underwriting Stability

The Bureau of Labor Statistics reports that the accommodation and food services sector consistently runs annual turnover rates above 70–75%. From an insurance carrier’s perspective, a group that turns over 70% of its employees each year is essentially a different group every 12 months. That uncertainty gets priced into your renewal — sometimes brutally.

Practically speaking, this means you are also dealing with constant enrollment and termination paperwork, COBRA notices, and waiting period management. The administrative cost of running benefits for a churning hourly workforce is often underestimated by at least 30–40 hours of HR time per year.

3. Variable Schedules Create ACA Eligibility Complexity

Under the ACA, employees who average 30+ hours per week over a measurement period must be offered coverage or the employer faces potential penalties. For a restaurant with a mix of full-time kitchen staff, part-time servers, and seasonal workers, calculating who is eligible — and proving it — requires either a solid HR system or a dedicated person watching hours weekly.

Restaurants with 50 or more full-time equivalent employees are Applicable Large Employers (ALEs) under the ACA and face stricter reporting requirements under IRS Section 4980H. Even operators with fewer than 50 FTEs can find themselves unexpectedly reclassified as the business grows.

What Are Your Real Options for Restaurant Health Benefits?

Given these structural challenges, here is an honest look at the practical paths available to restaurant operators in 2026.

Option 1: Traditional Small-Group Plan (Works If You Have Stable Core Staff)

If you have 10–15 full-time employees who have been with you more than a year and are willing to enroll, a traditional small-group plan through a regional or national carrier can still be cost-effective. Expect to pay $550–$750 per enrolled employee per month for a mid-tier plan, and budget for a 6–12% annual renewal increase based on recent market trends.

This path gets difficult fast if your full-time count is under 10, your staff is primarily part-time, or you have had even one high-claims year. One hospitalization can spike a small group’s renewal by 20–30%.

Option 2: ICHRA — The Part-Time Friendly Alternative

An Individual Coverage Health Reimbursement Arrangement (ICHRA) lets you give employees a fixed monthly dollar amount — say $300 for part-timers, $500 for full-timers — that they use to buy their own marketplace plan. You control the budget. They control the plan. There is no participation requirement and no group underwriting.

ICHRAs work especially well for variable-schedule restaurants because you can set different allowances for different classes of employees (full-time vs. part-time vs. seasonal). The downside: employees in states with limited marketplace options or high premiums may find the allowance does not go very far, and you lose the ability to offer a single unified plan as a recruiting tool.

Option 3: PEO Group Pooling — Access Large-Employer Rates on a Small Budget

This is where the math starts to work differently. A Professional Employer Organization (PEO) co-employs your workforce alongside hundreds or thousands of other businesses. Because the PEO’s total headcount might be 10,000–50,000 employees, it negotiates health insurance as a large employer — getting access to carrier networks, plan designs, and premium rates that a 20-person restaurant simply cannot touch on its own.

According to NAPEO, businesses that use PEOs grow 7–9% faster and have 10–14% lower employee turnover than comparable companies that do not. For restaurants specifically, lower turnover has a direct dollar value: replacing a line cook typically costs $1,500–$3,000 in recruiting and training time.

The participation requirement problem largely disappears inside a PEO because enrollment is calculated across the entire PEO’s book of business, not just your 18 employees. Employees who opt out of your restaurant’s plan are still part of the PEO’s broader pool. That means you can offer real benefits without needing every employee to sign up on day one.

Based on our analysis of 100+ PEO providers at PEO Marketplace, restaurant operators with 10–75 employees typically see health insurance savings of 10–25% compared to comparable small-group plans — largely because of this pooling effect. If you want to see what options apply to your headcount and location, our guide to the best PEOs for small businesses walks through the top-rated providers by industry.

Option 4: Voluntary / Supplemental Benefits as a Starting Point

If full medical coverage is not yet financially realistic, voluntary benefits — accident insurance, critical illness coverage, hospital indemnity, telemedicine access — can be offered at zero or near-zero employer cost. Employees pay the premium through payroll deduction, but they get group rates they could not access on their own.

This is not a replacement for health insurance, but it is a meaningful step that shows your team you are trying. In tight labor markets, that matters for retention even if the benefit itself is modest.

How to Calculate What You Can Actually Afford

Before shopping plans, build a simple model. Take your expected enrollment (be conservative — assume 50–60% of eligible staff), multiply by your maximum monthly employer contribution, and see what that annual budget looks like. Then compare that budget against plan options from a broker or a PEO.

For example: 15 enrollees × $400/month employer contribution = $72,000/year health insurance budget. At that number, you have real options — particularly if you are willing to consider a high-deductible plan paired with an employer-funded HSA contribution. Our PEO cost calculator can show you how a pooled arrangement compares to that budget in under two minutes.

If you want to benchmark what restaurants your size and region are actually paying before committing to anything, our free Benefits Benchmark Report breaks down real premium data by industry and headcount.

The Real Cost of Not Offering Health Insurance

It is easy to focus on the premium line and decide you cannot afford benefits. But the math changes when you factor in what turnover actually costs. If your restaurant has 30 employees and annual turnover of 70%, you are replacing roughly 21 people per year. At a conservative replacement cost of $1,500 per hourly employee, that is $31,500 in annual turnover cost — before you account for lost productivity, training time, and the impact on customer experience.

KFF data shows that employees consistently rank health benefits as the second most important factor in job selection after salary. In a market where every QSR and casual dining chain within two miles is competing for the same labor pool, a credible benefits package is one of the few differentiators a independent operator can control.


Ready to See What Health Benefits Would Actually Cost Your Restaurant?

At PEO Marketplace, we match restaurant operators with vetted benefits providers and PEOs that specialize in food service — no broker commissions, no upselling, just an honest comparison. Book a free 20-minute call and we will show you exactly what your team could access and what it would cost.

Book a Free Consultation →

Not ready to book a call? Get a free Benefits Benchmark Report for your industry — we will email you a breakdown of what companies your size are paying for HR, benefits, and workers comp so you can compare on your own timeline.

Get My Free Benchmark Report →


Frequently Asked Questions

How much does it cost a restaurant to offer health insurance per employee?

In 2026, the average restaurant employer pays $6,800–$9,000 per enrolled employee per year for single health coverage, depending on plan type and location. High-deductible plans and level-funded arrangements can bring that number closer to $5,000–$6,500 for younger, healthier workforces typical in food service.

Do restaurants have to offer health insurance?

Restaurants with 50 or more full-time equivalent employees are required under the ACA to offer minimum essential coverage to full-time employees or face IRS penalties. Restaurants with fewer than 50 FTEs are not legally required to offer health insurance, but many choose to do so for competitive recruiting reasons.

Why is it so hard for restaurants to get small-group health insurance?

Small-group carriers typically require 70% of eligible employees to enroll, which is difficult to achieve with hourly staff who prefer the extra take-home pay. High turnover also makes carriers nervous about underwriting stability, often resulting in higher premiums or outright coverage denials for small restaurant groups.

What is an ICHRA and is it good for restaurant workers?

An Individual Coverage HRA (ICHRA) is an employer-funded account that gives employees a set monthly dollar amount to purchase their own health insurance on the ACA marketplace. ICHRAs are well-suited for restaurants because there is no participation requirement, employers control the budget, and you can set different allowance amounts for full-time versus part-time workers.

Can a small restaurant afford to offer health benefits competitively?

Yes — particularly by joining a group purchasing arrangement through a PEO or using an ICHRA structure that caps employer costs at a fixed monthly contribution. Based on our experience matching hundreds of restaurant operators, even $250–$400 per employee per month in employer contributions can unlock meaningful coverage when combined with the right plan structure or pooled buying power.

What Is ACA Affordability and Why It Matters in 2026?

Under the Affordable Care Act, an employer-sponsored health plan is considered affordable if the employee’s required contribution for self-only coverage does not exceed a specific percentage of their household income for the year. For 2026, the IRS publishes the exact affordability threshold annually — employers should confirm the current-year percentage directly on IRS.gov before running their calculations, as it adjusts each plan year. Businesses approaching or already over 50 full-time equivalent employees (FTEs) need to get this right: failure to offer an affordable plan can trigger significant Employer Shared Responsibility Payments (ESRPs) under IRC Section 4980H(b).

Affordable Care Act compliance is not just a large-company problem. If your headcount is anywhere near the 50-FTE threshold, you are likely an Applicable Large Employer (ALE) or will be soon — and ALE status means the affordability rules apply to you. This guide walks through exactly how the affordability test works, the three IRS-approved safe harbors you can use, and what happens if a plan fails the test.

How Does the ACA Affordability Test Work?

The affordability test compares what an employee pays for the lowest-cost, self-only plan you offer to that employee’s household income. Because employers almost never know an employee’s actual household income, the IRS created three safe harbors — calculation methods that, if used correctly, protect employers from ESRP exposure even if an employee’s actual household income turns out to be different.

Here is the core logic: if the employee’s required monthly premium contribution for self-only minimum essential coverage (MEC) does not exceed the IRS threshold percentage of the applicable income figure under the safe harbor you choose, your plan is deemed affordable for that employee. The test applies to the lowest-cost self-only option you make available — not the plan the employee actually enrolls in.

Why the Lowest-Cost Plan Is the Benchmark

Many employers offer tiered plan options — bronze, silver, gold. For affordability purposes, what matters is whether the cheapest self-only MEC plan you offer passes the test. If an employee can access an affordable option but chooses a more expensive tier, you are still compliant for that employee. This means your benefit design strategy and your affordable-tier pricing are directly linked to your ACA exposure.

Wondering if a PEO could get your team better benefits for less? Run the numbers yourself — our free calculator shows you what companies your size are actually paying.

Try the Free Calculator →

The Three ACA Safe Harbors Every Employer Should Know

Because employers cannot realistically verify each employee’s household income, the IRS established three safe harbors for 2026. Each one uses a different income proxy, and each has practical trade-offs. You can use different safe harbors for different classes of employees, as long as you apply each one consistently within that class.

1. The W-2 Safe Harbor

Under the W-2 safe harbor, a plan is affordable if the employee’s required contribution for self-only coverage does not exceed the IRS threshold percentage of the employee’s W-2 wages (Box 1) from the prior calendar year. This is the most straightforward method for salaried employees with predictable, stable pay. However, it creates a potential timing mismatch: you need to set contribution amounts for the upcoming plan year before the W-2 is finalized. Employers typically use the prior year’s W-2 as a proxy and adjust plan pricing accordingly. This safe harbor can also be tricky for new hires or employees whose hours vary significantly, since their W-2 wages may not yet reflect a full year of earnings.

2. The Rate of Pay Safe Harbor

The rate of pay safe harbor is generally the most employer-friendly option for hourly workers. For hourly employees, multiply the employee’s hourly rate as of the first day of the plan year by 130 hours (the IRS-defined full-time hours threshold per month) to get a monthly income proxy. For salaried employees, use their monthly salary. If the required contribution does not exceed the IRS percentage of that monthly figure, the plan is affordable under this safe harbor. The key advantage: you can calculate affordability before the year begins, because you are using current rates rather than looking back at W-2 data. The limitation is that it cannot be used if an employee’s hourly rate dropped during the year — you must use the lowest rate in that scenario.

3. The Federal Poverty Line (FPL) Safe Harbor

The FPL safe harbor is the simplest to administer and the one most likely to result in a passing test — but it may require the lowest employee contribution, meaning higher employer cost. Under this method, a plan is affordable if the required contribution for self-only coverage does not exceed the IRS threshold percentage of the Federal Poverty Line for a single individual (published annually by HHS). Because the FPL is a fixed, publicly available number, every employee is treated the same regardless of their individual wages. This safe harbor works especially well for employers with a large hourly workforce, high turnover, or complex payroll structures where tracking individual rates is administratively difficult. Check the current FPL figures at HHS.gov each plan year.

Safe HarborIncome Proxy UsedBest ForMain Watch-Out
W-2Prior-year Box 1 wagesSalaried, full-year employeesTiming mismatch; tricky for new hires
Rate of PayHourly rate × 130 hrs or monthly salaryHourly workers, predictable schedulingCannot use if rate dropped mid-year
Federal Poverty LineFPL for a single personHigh-turnover or complex workforcesMay require lowest employee contribution

What Happens When a Health Plan Fails the Affordability Test?

When a plan fails the ACA affordability test, the consequences fall under Section 4980H(b) of the Internal Revenue Code — sometimes called the “B Penalty” or the “affordability penalty.” An employer is only exposed to this penalty if at least one full-time employee receives a premium tax credit (PTC) through a Marketplace plan. The IRS does not automatically assess the penalty — it is triggered by employee Marketplace enrollments and the subsequent IRS matching process.

How the ESRP Penalty Is Calculated

The 4980H(b) ESRP is assessed monthly, per full-time employee who actually receives a PTC through the Exchange. The penalty amount is set by the IRS and adjusted annually — confirm the current dollar figure for 2026 on IRS.gov. The key distinction from the 4980H(a) penalty (for failing to offer coverage at all) is that the (b) penalty only applies to employees who actually go to the Marketplace and receive a subsidy — not to your entire workforce. That said, even a handful of employees triggering PTC claims can result in tens of thousands of dollars in annual exposure for a mid-size employer.

The IRS Notification Process

The IRS identifies potential ESRP liability through the ACA information reporting employers file — Forms 1094-C and 1095-C. The agency matches those filings against individual tax returns where employees claimed PTCs, then issues Letter 226-J to employers with proposed ESRP assessments. Employers have a defined window to respond and dispute the proposed assessment. Accurate, timely 1094-C/1095-C filing is your first line of defense — errors or missing data make it harder to challenge an incorrect penalty notice.

How a PEO Can Take ACA Compliance Off Your Plate

For employers near or over the 50-FTE threshold, ACA tracking, safe harbor calculations, and 1094-C/1095-C reporting represent a significant administrative burden — especially if your workforce includes a mix of full-time, part-time, and variable-hour employees. This is one area where a Professional Employer Organization (PEO) delivers measurable value beyond payroll processing.

A PEO takes on co-employer responsibilities for your workforce, which typically includes managing ACA measurement periods, running affordability calculations, and filing ACA reporting on your behalf. In our experience matching hundreds of businesses through PEO Marketplace, ACA compliance administration is one of the top three reasons employers in the 40–100 FTE range decide to move to a PEO. According to NAPEO, businesses that use a PEO grow 7–9% faster and have 10–14% lower employee turnover than comparable companies that do not — and reduced compliance risk is a core driver of that outcome.

If you are evaluating PEO options, it is worth understanding how different providers handle ACA reporting as part of their service model. Some fully absorb it; others treat it as an add-on. Our guide to the best PEOs for small business breaks down what to look for. You can also review our Insperity cost comparison to see how one of the larger PEOs structures its compliance services relative to competitors.

What to Ask a PEO About ACA Before You Sign

Not all PEOs handle ACA the same way. Before committing, ask specifically: Does the PEO file 1094-C and 1095-C under their own EIN or yours? Who runs the measurement period tracking for variable-hour employees? What happens if an affordability calculation error results in a penalty — who bears that liability? The answers to these questions will tell you a lot about how serious a given provider is about ACA compliance versus treating it as a checkbox.

2026 ACA Affordability: Key Takeaways for Employers

ACA affordability in 2026 comes down to a clear framework: know your IRS threshold percentage (confirm it at IRS.gov), choose the right safe harbor for each employee class, price your lowest-cost plan accordingly, and file accurate 1094-C/1095-C reports on time. If you are managing this manually across a workforce of 50 or more employees, the administrative complexity compounds quickly — especially when you layer in variable-hour workers, seasonal staff, and mid-year new hires.

Whether you handle ACA compliance in-house or explore a PEO partnership, the math matters. Use our free PEO cost calculator to see what employers your size are actually paying for HR and benefits administration — including ACA compliance services — so you have a real benchmark before making any decisions.

Ready to stop managing ACA compliance manually?

Book a free 15-minute call with a PEO Marketplace advisor. We will match you with vetted providers that handle ACA tracking, safe harbor calculations, and 1095-C filing — at no cost to you.

Book My Free PEO Consultation →

Not ready to book a call? Get a free Benefits Benchmark Report for your industry — we will email you a breakdown of what companies your size are paying for HR, benefits, and workers comp so you can compare on your own timeline.

Get My Free Benchmark Report →

Frequently Asked Questions About ACA Affordability

What is the ACA affordability percentage for 2026?

The IRS adjusts the ACA affordability percentage annually and publishes it in a revenue procedure each fall. Employers should confirm the exact 2026 figure directly on IRS.gov before calculating employee contributions, as guessing or using a prior-year number can result in a plan that technically fails the test.

Does the affordability test apply to dependent or family coverage?

No — the ACA affordability test applies only to the employee’s required contribution for self-only coverage, not to the cost of adding dependents or a spouse. However, starting in 2025, the “family glitch” fix from the IRS means dependents’ eligibility for Marketplace tax credits is also affected by the affordability of family-tier coverage, which is a separate but related compliance consideration.

Can I use different safe harbors for different groups of employees?

Yes, employers may use different safe harbors for different employee classifications — for example, the rate of pay safe harbor for hourly workers and the W-2 safe harbor for salaried employees. The IRS requires that each safe harbor be applied consistently to all employees within a reasonable classification, so document your methodology clearly for each group.

What is Form 1095-C and who needs to file it?

Form 1095-C is the ACA information return that Applicable Large Employers must furnish to full-time employees and file with the IRS alongside Form 1094-C. It reports whether coverage was offered, the employee’s required contribution, and the safe harbor code used — this is the data the IRS uses to identify potential ESRP liability. ALEs must file these forms annually, with deadlines set by the IRS for each reporting year.

Does a PEO file ACA forms on my behalf?

Many PEOs do file Forms 1094-C and 1095-C as part of their co-employment service, though the specific arrangement varies by provider — some file under their own EIN, others file under the client employer’s EIN. Before selecting a PEO, confirm exactly who bears filing responsibility and what liability the PEO accepts if an error leads to a proposed ESRP assessment. Our comparison of leading PEOs covers how different providers approach this.

The Short Answer

When comparing HR outsourcing companies, there are four primary models: PEO (Professional Employer Organization), ASO (Administrative Services Organization), HRO (Human Resources Outsourcing), and EOR (Employer of Record). Each model differs in who holds employer liability, what services are bundled, and how pricing is structured. Choosing the wrong model means paying for services you do not need or missing protections you do.

Why the Model You Choose Matters More Than the Vendor

Most business owners shopping for HR help start by comparing vendors — Gusto vs. Rippling, Insperity vs. TriNet. That is the wrong starting point. The model determines your legal exposure, your cost structure, and whether you can actually get the HR support your business needs at your stage of growth.

Based on our analysis of 40+ vetted PEOs and the businesses that work with them, the most common and costly mistake is selecting a model that fits a vendor’s sales pitch rather than the company’s actual risk profile and HR workload. This guide lays out the four models with no slant toward any one of them.

According to NAPEO, more than 500 PEOs operate in the United States, covering roughly 4 million worksite employees — but PEOs represent just one of several outsourcing structures worth evaluating.

Comparing PEOs is easier when you know your baseline cost. The PEO Calculator shows what a PEO would cost for your company in 60 seconds, with no call needed.

Try the PEO Calculator →

What Is a PEO (Professional Employer Organization)?

A PEO enters a co-employment relationship with your business. Your employees remain yours day-to-day, but the PEO becomes the employer of record for tax and benefits purposes. This means payroll taxes are filed under the PEO’s Employer Identification Number, and employees gain access to the PEO’s large-group benefit plans.

Who Holds Employer Liability in a PEO

Liability is shared. The PEO assumes responsibility for payroll tax compliance, benefits administration, and many HR compliance risks. You retain control over hiring, firing, and day-to-day management. This shared liability model is what distinguishes a PEO from every other outsourcing structure.

What Is Included in a PEO

  • Payroll processing and tax filing under the PEO’s EIN
  • Large-group health, dental, vision, and ancillary benefits
  • Workers compensation coverage and claims management
  • HR compliance support and employee handbook assistance
  • Dedicated HR support (varies by provider)
  • Access to 401(k) and other retirement plans

PEO Pricing Structure

PEOs typically charge either a percentage of gross payroll (most common, usually 2–6%) or a flat per-employee-per-month (PEPM) fee ranging from $80 to $200+. Benefits premiums are often separate. You can get a baseline number for your headcount and payroll using the PEO Calculator.

Ideal Company Profile for a PEO

PEOs deliver the most value for businesses with 5–250 employees that want to offer competitive benefits without paying large-group premiums on their own, need compliance infrastructure without hiring a full HR department, and are willing to operate within the PEO’s benefit plan structure. According to NAPEO, PEO clients grow 7–9% faster and have 10–14% lower employee turnover than companies not using a PEO.

What Is an ASO (Administrative Services Organization)?

An ASO provides the same administrative HR services as a PEO — payroll, compliance support, benefits administration — but without co-employment. You remain the sole employer of record. The ASO works as a service vendor, not a legal co-employer.

Who Holds Employer Liability in an ASO

You do. The ASO processes payroll and manages HR tasks on your behalf, but all employer tax liabilities, workers compensation obligations, and compliance risks stay with your business. The ASO does not absorb any legal employer risk.

What Is Included in an ASO

  • Payroll processing under your EIN
  • Benefits administration (you source and own the plans)
  • HR compliance guidance and document management
  • Employee self-service technology platforms
  • Onboarding and offboarding support

ASO Pricing Structure

ASOs typically charge a flat PEPM fee ($20–$80 depending on service scope) or a percentage of payroll. Because you source your own benefits separately, the total cost of an ASO arrangement plus standalone benefits is often higher than a comparable PEO — especially for smaller companies that cannot negotiate group rates.

Ideal Company Profile for an ASO

ASOs work best for mid-size businesses (100+ employees) that already have competitive benefits in place, have an internal HR team that needs administrative support rather than strategic guidance, and want to retain full control over benefits plan design without joining a PEO’s master plan.

What Is an HRO (Human Resources Outsourcing)?

HRO is the broadest and most flexible category. It refers to outsourcing specific HR functions — recruiting, training, performance management, benefits consulting, compliance audits — to one or more specialized vendors. Unlike PEOs and ASOs, HRO is not a single bundled relationship; it is a menu of services assembled to fill gaps in an internal HR operation.

Who Holds Employer Liability in an HRO

You retain all employer liability. HRO vendors provide expertise and execution on defined deliverables. They do not assume any co-employment relationship or statutory employer obligations.

What Is Included in an HRO

  • Recruiting and talent acquisition (RPO)
  • Learning and development program delivery
  • Benefits consulting and broker services
  • HR technology implementation and support
  • Compliance auditing and policy development
  • Compensation benchmarking and total rewards design

HRO Pricing Structure

HRO pricing varies widely by function. Recruiting RPO engagements may be fee-per-hire or monthly retainer. Benefits consulting is often project-based or commission-based through broker relationships. Technology platforms charge PEPM fees. The total investment depends entirely on which functions are outsourced and at what scope.

Ideal Company Profile for an HRO

HRO is the right model for larger companies (250+ employees) with an established internal HR team that needs specialized support for specific functions, or for companies undergoing rapid growth that need recruiting or training capacity without permanent headcount. It is not efficient for small businesses that need broad HR coverage — the administrative overhead of managing multiple vendors quickly outweighs the flexibility.

What Is an EOR (Employer of Record)?

An EOR becomes the legal employer of your workers in a specific jurisdiction — most commonly used when hiring internationally or in states where you lack a legal entity. The EOR handles all local employment law compliance, payroll, taxes, and statutory benefits on your behalf. You direct the work; the EOR owns the employment relationship on paper.

Who Holds Employer Liability in an EOR

The EOR holds full employer liability in that jurisdiction. This is the most complete transfer of employer risk of any model — which also means less control over local benefits and employment terms than you would have with a local entity.

What Is Included in an EOR

  • Legal entity in the target country or state
  • Local payroll processing and tax remittance
  • Statutory benefits compliance (health, leave, pension per local law)
  • Employment contracts drafted to local standards
  • Termination and offboarding in compliance with local law

EOR Pricing Structure

EOR providers typically charge $500–$2,000+ per employee per month depending on the country, local complexity, and service tier. Pricing is notably higher than domestic HR outsourcing because the EOR is absorbing full legal employer risk in a foreign or unfamiliar jurisdiction.

Ideal Company Profile for an EOR

EORs are purpose-built for companies expanding internationally without establishing a local entity, or hiring a small number of remote workers in states where they have no payroll registration. For domestic multi-state hiring at scale, the per-employee cost of an EOR usually makes a PEO the more economical option. The IRS guidance on employer identification provides useful context on EIN responsibilities that an EOR assumes on your behalf.

Side-by-Side Comparison: PEO vs ASO vs HRO vs EOR

FeaturePEOASOHROEOR
Co-employmentYesNoNoYes (full)
Employer liabilitySharedClient onlyClient onlyEOR only
Payroll EINPEO’s EINYour EINYour EINEOR’s EIN
Benefits accessLarge-group plansYour own plansConsulting onlyStatutory only
Typical pricing2–6% payroll or $80–$200 PEPM$20–$80 PEPMVariable by function$500–$2,000+ PEPM
Best employee count5–250100+250+1–50 (international)
Workers comp includedYesNoNoYes (local)
Use caseSMB full HR stackAdmin support, own benefitsFill specific HR gapsInternational or remote hiring

How to Choose the Right HR Outsourcing Model

The right model depends on three variables: how many employees you have, how much employer liability you want to transfer, and whether benefits access is a strategic priority.

Choose a PEO if

You have 5–250 employees, want to offer Fortune 500-caliber benefits without self-insuring, and need broad HR compliance coverage without building an internal HR team. Businesses that want to save 20–40% on operational and benefit costs compared to managing benefits independently often find the PEO model the most cost-efficient path at this size. See how leading PEOs for small businesses compare on this criteria.

Choose an ASO if

You already have strong benefits in place, want to keep your own EIN and benefit plan design, and simply need better HR technology and administrative support. This is common for mid-size companies that have outgrown startup-era HR tools but are not ready for the co-employment structure a PEO requires.

Choose HRO if

You have an internal HR team and need to outsource specific, high-skill functions — talent acquisition, compensation benchmarking, or compliance auditing — without touching your core employer structure. The Department of Labor’s compliance assistance resources can help you identify which compliance gaps are most common at your size before engaging an HRO.

Choose an EOR if

You are hiring workers in countries or states where you have no legal entity and want zero exposure to local employment law complexity. EOR is a bridge solution, not a permanent infrastructure — most companies eventually establish their own entity once headcount in a region justifies it.

A Note on Hybrid Arrangements

Some providers offer combinations. A PEO may also offer EOR services for international contractors. An HRO vendor may bundle ASO-style payroll administration. In our experience matching hundreds of businesses with HR solutions, hybrid arrangements often signal that a provider is trying to cover a broader market rather than delivering specialized depth. Evaluate what you actually need before accepting a bundled offer that includes services you will not use.

If you are specifically evaluating PEO vendors side by side, the Gusto vs. Justworks comparison and the Insperity cost breakdown are useful starting points for understanding how pricing and service scope differ across named providers.

Next Steps

If you have identified the right model and want to compare specific providers within it, PEO Marketplace works with 40+ vetted PEOs and can match your business to the best-fit options based on your industry, headcount, and benefits priorities — without a sales push toward any single vendor.

Schedule a Matching Consultation →

Prefer to compare on your own timeline first. Run the Benefits Benchmark for your industry and we will email you a breakdown of what companies your size are paying for HR, benefits and workers comp.

Run the Benefits Benchmark →

Frequently Asked Questions

What is the difference between a PEO and an EOR?

A PEO enters a co-employment arrangement where employer liability is shared between the PEO and your business, and your employees are filed under the PEO’s EIN for payroll and benefits purposes. An EOR becomes the full legal employer in a specific jurisdiction, typically used for international or remote hires where you have no registered entity — the EOR assumes all local employer liability, not just a share of it.

Is a PEO or an ASO better for a small business?

For most businesses under 100 employees, a PEO delivers more value than an ASO because the co-employment structure unlocks large-group benefit rates that an ASO arrangement cannot access. An ASO makes more sense when you already have established, competitive benefit plans and primarily need administrative support and HR technology.

Does using an EOR mean I give up control of my employees?

An EOR becomes the legal employer on paper, but you retain full control over the work your employees perform, their daily management, and their role within your organization. The EOR’s control is limited to the employment law and payroll compliance side of the relationship in the relevant jurisdiction.

How do I know if my company needs HRO instead of a PEO?

If your business already has an internal HR team and you need to fill specific gaps — such as recruiting capacity, compliance auditing, or leadership training — HRO is likely the better fit because you are buying expertise for defined functions rather than a full HR infrastructure replacement. A PEO is better suited when you need end-to-end HR coverage and do not have a dedicated HR team managing day-to-day needs.

Can a company use more than one HR outsourcing model at the same time?

Yes, and many growing companies do. A common combination is a PEO for domestic employees paired with an EOR for international hires in countries where the company has no legal entity. The key is ensuring the two arrangements do not create conflicting employer-of-record designations for the same employees or jurisdictions.

The seven most common payroll tax mistakes small businesses make are late tax deposits, using the wrong deposit schedule, errors on Form 941, missed state filings, mishandling fringe benefit taxation, worker misclassification, and late or incorrect W-2s. Each one carries a specific IRS penalty structure that compounds fast. Getting even one of these wrong can cost a business thousands of dollars in penalties, interest, and professional fees to clean up.

If you are running payroll yourself or relying on basic software without expert oversight, the risk is higher than most owners realize. This guide walks through each mistake, what the IRS actually charges, and how to protect your business before a notice arrives.

Why Payroll Tax Compliance Is Harder Than It Looks

Payroll tax compliance means accurately calculating, withholding, depositing, and reporting federal and state payroll taxes on the correct schedule — every pay period, without exception. The IRS does not distinguish between honest mistakes and willful violations when it comes to calculating penalties. The Federal Trust Fund Recovery Penalty, outlined on IRS.gov, can hold business owners personally liable for unpaid payroll taxes — even if the business entity itself closes.

According to the IRS, employment tax penalties are among the most frequently assessed against small businesses. The complexity comes from the intersection of federal deposit rules, state agency requirements, quarterly reporting deadlines, and classification rules — all of which change regularly.

Find out whether a PEO makes sense for your business. The PEO Calculator shows you the real cost in 60 seconds, with no call and no commitment.

Try the PEO Calculator →

The 7 Payroll Tax Mistakes That Trigger IRS Penalties

1. Late Tax Deposits

Late payroll tax deposits are the single most common trigger for IRS penalties on small businesses. The IRS assesses a tiered failure-to-deposit penalty that starts at 2% for deposits 1–5 days late and climbs to 15% for amounts still unpaid more than 10 days after a notice is issued. On a $20,000 payroll tax liability, a 10% penalty alone is $2,000 — before interest accrues.

Deposits must be made through the Electronic Federal Tax Payment System (EFTPS). Wire transfers or checks sent to the IRS do not count as timely deposits. Many owners using basic payroll software assume the software is handling deposits automatically when it is not configured to do so, leading to surprise penalties months later.

2. Using the Wrong Deposit Schedule

The IRS assigns businesses either a monthly or semi-weekly deposit schedule based on the total taxes reported during a lookback period — the 12-month period ending June 30 of the prior year. If your total employment tax liability during that period was $50,000 or less, you deposit monthly. If it exceeded $50,000, you must deposit semi-weekly.

Businesses that grow quickly often miss the transition from monthly to semi-weekly depositor status. Depositing on a monthly schedule when semi-weekly is required results in late-deposit penalties on every paycheck cycle. The IRS publishes the deposit schedule rules in Publication 15 (Circular E), and reviewing it at the start of each calendar year is essential.

3. Form 941 Errors

Form 941 is the quarterly payroll tax return that reconciles your deposits against what you owe in federal income tax withholding, Social Security, and Medicare taxes. Common errors include transposed employee counts, math errors in tax calculations, missing signatures, and failing to account for mid-quarter hires or terminations.

An inaccurate Form 941 can trigger a discrepancy notice, force a manual reconciliation process, and generate interest charges on any understated balance. The IRS failure-to-file penalty for Form 941 is 5% of the unpaid tax for each month or partial month the return is late, up to 25%. Even a minor math error can flag your account for additional scrutiny.

4. Missed or Late State Payroll Tax Filings

Federal compliance is only half the equation. Every state with an income tax has its own withholding deposit schedules, quarterly or annual reconciliation returns, and unemployment insurance (SUI) filings. Some states also require local income tax withholding depending on where employees work — not where the business is headquartered.

Remote work has made this significantly more complicated. An employee working from a different state than your business address may create nexus in that state, triggering new registration, withholding, and filing obligations. Missing a state filing carries its own penalty structure independent of the IRS, and in some states, the penalties exceed federal rates. The Department of Labor’s unemployment insurance page is a useful starting point for understanding state-level SUI obligations.

5. Mishandling Fringe Benefit Taxation

Fringe benefits that are not properly excluded under IRS rules are taxable wages and must be included in payroll. Common examples include personal use of a company vehicle, employer-paid life insurance over $50,000, non-qualifying moving expense reimbursements, and certain gifts or awards above the de minimis threshold.

Many small business owners either omit taxable fringe benefits from payroll entirely or assume all benefits are tax-exempt. When these amounts are not included in taxable wages, the business underpays FICA taxes and income tax withholding, which triggers both deposit penalties and potential reclassification of the benefit as compensation during an audit. IRS Publication 15-B covers the rules for fringe benefit exclusions in detail.

6. Worker Misclassification

Classifying an employee as an independent contractor to avoid payroll taxes is one of the highest-risk payroll errors a business can make. The IRS uses a multi-factor behavioral and financial control test to determine whether a worker is truly an independent contractor. When misclassification is found, the business becomes liable for the employer’s share of FICA taxes, the employee’s share that should have been withheld, federal income tax withholding, and applicable penalties and interest — often covering multiple tax years simultaneously.

The IRS Voluntary Classification Settlement Program (VCSP) allows businesses to proactively reclassify workers and pay a reduced penalty, but only before an audit begins. The VCSP details are available on IRS.gov. If a misclassification issue is discovered during an audit, the full penalty structure applies with no reduction option.

7. Late or Incorrect W-2s

W-2s must be furnished to employees by January 31 and filed with the Social Security Administration by the same date. The penalty for failure to file a correct W-2 by the deadline ranges from $60 to $310 per form for 2026, depending on how late the filing is and whether the error was due to intentional disregard. For a business with 25 employees that files W-2s even 30 days late, the penalty exposure can reach $4,650 or more.

Common W-2 errors include incorrect Social Security numbers, wrong employer EIN, missing Box 12 codes for deferred compensation or health coverage, and totals that do not reconcile with quarterly Form 941 submissions. These discrepancies flag your account with both the IRS and SSA, often leading to notices and additional back-and-forth that consumes significant time.

How Payroll Complexity Compounds Over Time

Each of these seven mistakes is solvable in isolation. The real danger is that they tend to compound. A business that misclassifies a worker may also be omitting their fringe benefits from payroll, depositing on the wrong schedule, and missing state filings for the states where those workers operate. When the IRS opens an examination, all of these issues surface together.

According to data from NAPEO, businesses that outsource HR and payroll functions through a professional employer organization spend significantly less time on administrative compliance and report fewer penalty events. Based on our analysis of 40+ vetted PEOs, one of the most consistent reasons business owners move to a structured HR solution is specifically to transfer payroll tax filing responsibility away from themselves or an overloaded office manager.

How a PEO Transfers Payroll Tax Filing Responsibility

A Professional Employer Organization (PEO) enters into a co-employment arrangement with your business. In that arrangement, the PEO becomes the employer of record for tax purposes and assumes responsibility for calculating, depositing, and filing your federal and state payroll taxes — including Form 941, W-2s, and state unemployment returns.

This is not just administrative convenience. Under a PEO relationship, the PEO’s EIN is used for tax filings, and the PEO carries the compliance burden and infrastructure to stay current on deposit schedules, state registration requirements, and fringe benefit classification rules. For small businesses that lack a dedicated payroll tax specialist, this transfer of responsibility eliminates the exposure points outlined above.

Businesses working with PEOs also gain access to group-rate benefits purchasing power. According to NAPEO, PEO clients grow 7–9% faster and have 10–14% lower employee turnover than comparable businesses. The compliance infrastructure is a core component of that advantage. If you are evaluating whether a PEO is the right fit, the guide to best PEOs for small businesses breaks down the options by company size and industry.

It is worth noting that not all PEOs handle payroll tax filing identically. Some PEOs file under their own EIN (fully assuming the tax responsibility), while others file under your EIN with shared responsibility. When comparing options, ask specifically how payroll tax deposits and employer filings are handled. The comparison of Gusto and Justworks is a useful reference for understanding how smaller PEO-adjacent platforms differ from full-service PEO arrangements on this dimension.

Steps to Reduce Payroll Tax Risk Right Now

Whether or not you ultimately move to a PEO, the following steps reduce your exposure to the penalties described above.

  • Confirm your deposit schedule at the start of each year by reviewing your lookback period liability against the IRS threshold.
  • Enroll in and actively use EFTPS for all federal payroll tax deposits. Do not rely on a software platform to do this without verifying that it is configured correctly.
  • Reconcile Form 941 to your payroll register before submitting each quarter. Total wages, withholding amounts, and employee counts should match exactly.
  • Audit worker classification annually, particularly for contractors who work exclusively for your business or who work on-site under your direction.
  • Map your state filing obligations against where employees physically work, not just where they were hired from.
  • Include taxable fringe benefits in payroll at the time they are provided, not at year-end when corrections become more complex.
  • Set a W-2 preparation deadline of January 15 internally so that errors can be corrected before the January 31 statutory deadline.

If you are unsure where your current process stands, the PEO matching service at PEO Marketplace can connect you with vetted providers who specialize in taking on exactly this kind of compliance responsibility for businesses your size.

What It Costs to Get This Wrong

MistakeIRS Penalty RangeAdditional Exposure
Late deposit2%–15% of deposit amountInterest on unpaid balance
Wrong deposit schedule2%–15% per periodCompounds each pay cycle
Form 941 errors / late filing5% per month, up to 25%IRS notice and audit risk
Missed state filingsVaries by stateState interest + possible liens
Fringe benefit omissionFICA underpayment penaltiesBack taxes + gross-up calculations
Worker misclassificationFull FICA + income tax + penaltiesPersonal liability via TFRP
Late or incorrect W-2s$60–$310 per formSSA discrepancy notices

Frequently Asked Questions

What is the IRS penalty for late payroll tax deposits?

The IRS assesses a failure-to-deposit penalty ranging from 2% for deposits 1–5 days late to 15% for amounts still unpaid more than 10 days after an IRS notice is issued. Interest accrues separately on top of the penalty until the balance is paid in full.

How does the IRS determine worker classification?

The IRS uses a behavioral control, financial control, and type-of-relationship test to determine whether a worker is an employee or independent contractor. Workers who are directed on how, when, and where to work, and who rely on the business as their primary source of income, are typically classified as employees regardless of contract language.

What happens if a small business misses a state payroll tax filing?

Missing a state payroll tax filing triggers state-specific penalties and interest that accrue independently of any federal issues. In some states, repeated missed filings can result in a tax lien against business assets or personal assets of the responsible owner or officer.

Can a PEO completely eliminate payroll tax penalty risk?

When a PEO files payroll taxes under its own EIN as the employer of record, it assumes the primary filing responsibility and significantly reduces the client business’s direct penalty exposure. The business still has an obligation to provide accurate payroll data to the PEO on time, so the risk is shared rather than entirely eliminated.

What is the Trust Fund Recovery Penalty and who does it apply to?

The Trust Fund Recovery Penalty (TFRP) allows the IRS to hold individual business owners, officers, or other responsible parties personally liable for unpaid payroll taxes — specifically the employee portion of Social Security and Medicare taxes and withheld income tax. It applies when the IRS determines that a responsible person willfully failed to collect or pay over those taxes, and it can survive business closure or bankruptcy.

If you want to understand what handing off payroll tax compliance to a vetted provider would actually cost for your business, a conversation with the team at PEO Marketplace takes less than 30 minutes and covers your specific headcount, state footprint, and industry. Schedule a time below.

Talk to a PEO matching specialist at PEO Marketplace

Based on our analysis of 40+ vetted PEOs, we match your business with providers that fit your size, state footprint, and compliance needs — with no pressure and no cost to you.

Schedule a Consultation →

Prefer to compare on your own timeline first. Run the Benefits Benchmark for your industry and we will email you a breakdown of what companies your size are paying for HR, benefits and workers comp.

Run the Benefits Benchmark →

Scroll to Top