PEO Workers Comp

What Is ACA Affordability and Why It Matters in 2026?

Under the Affordable Care Act, an employer-sponsored health plan is considered affordable if the employee’s required contribution for self-only coverage does not exceed a specific percentage of their household income for the year. For 2026, the IRS publishes the exact affordability threshold annually — employers should confirm the current-year percentage directly on IRS.gov before running their calculations, as it adjusts each plan year. Businesses approaching or already over 50 full-time equivalent employees (FTEs) need to get this right: failure to offer an affordable plan can trigger significant Employer Shared Responsibility Payments (ESRPs) under IRC Section 4980H(b).

Affordable Care Act compliance is not just a large-company problem. If your headcount is anywhere near the 50-FTE threshold, you are likely an Applicable Large Employer (ALE) or will be soon — and ALE status means the affordability rules apply to you. This guide walks through exactly how the affordability test works, the three IRS-approved safe harbors you can use, and what happens if a plan fails the test.

How Does the ACA Affordability Test Work?

The affordability test compares what an employee pays for the lowest-cost, self-only plan you offer to that employee’s household income. Because employers almost never know an employee’s actual household income, the IRS created three safe harbors — calculation methods that, if used correctly, protect employers from ESRP exposure even if an employee’s actual household income turns out to be different.

Here is the core logic: if the employee’s required monthly premium contribution for self-only minimum essential coverage (MEC) does not exceed the IRS threshold percentage of the applicable income figure under the safe harbor you choose, your plan is deemed affordable for that employee. The test applies to the lowest-cost self-only option you make available — not the plan the employee actually enrolls in.

Why the Lowest-Cost Plan Is the Benchmark

Many employers offer tiered plan options — bronze, silver, gold. For affordability purposes, what matters is whether the cheapest self-only MEC plan you offer passes the test. If an employee can access an affordable option but chooses a more expensive tier, you are still compliant for that employee. This means your benefit design strategy and your affordable-tier pricing are directly linked to your ACA exposure.

Wondering if a PEO could get your team better benefits for less? Run the numbers yourself — our free calculator shows you what companies your size are actually paying.

Try the Free Calculator →

The Three ACA Safe Harbors Every Employer Should Know

Because employers cannot realistically verify each employee’s household income, the IRS established three safe harbors for 2026. Each one uses a different income proxy, and each has practical trade-offs. You can use different safe harbors for different classes of employees, as long as you apply each one consistently within that class.

1. The W-2 Safe Harbor

Under the W-2 safe harbor, a plan is affordable if the employee’s required contribution for self-only coverage does not exceed the IRS threshold percentage of the employee’s W-2 wages (Box 1) from the prior calendar year. This is the most straightforward method for salaried employees with predictable, stable pay. However, it creates a potential timing mismatch: you need to set contribution amounts for the upcoming plan year before the W-2 is finalized. Employers typically use the prior year’s W-2 as a proxy and adjust plan pricing accordingly. This safe harbor can also be tricky for new hires or employees whose hours vary significantly, since their W-2 wages may not yet reflect a full year of earnings.

2. The Rate of Pay Safe Harbor

The rate of pay safe harbor is generally the most employer-friendly option for hourly workers. For hourly employees, multiply the employee’s hourly rate as of the first day of the plan year by 130 hours (the IRS-defined full-time hours threshold per month) to get a monthly income proxy. For salaried employees, use their monthly salary. If the required contribution does not exceed the IRS percentage of that monthly figure, the plan is affordable under this safe harbor. The key advantage: you can calculate affordability before the year begins, because you are using current rates rather than looking back at W-2 data. The limitation is that it cannot be used if an employee’s hourly rate dropped during the year — you must use the lowest rate in that scenario.

3. The Federal Poverty Line (FPL) Safe Harbor

The FPL safe harbor is the simplest to administer and the one most likely to result in a passing test — but it may require the lowest employee contribution, meaning higher employer cost. Under this method, a plan is affordable if the required contribution for self-only coverage does not exceed the IRS threshold percentage of the Federal Poverty Line for a single individual (published annually by HHS). Because the FPL is a fixed, publicly available number, every employee is treated the same regardless of their individual wages. This safe harbor works especially well for employers with a large hourly workforce, high turnover, or complex payroll structures where tracking individual rates is administratively difficult. Check the current FPL figures at HHS.gov each plan year.

Safe HarborIncome Proxy UsedBest ForMain Watch-Out
W-2Prior-year Box 1 wagesSalaried, full-year employeesTiming mismatch; tricky for new hires
Rate of PayHourly rate × 130 hrs or monthly salaryHourly workers, predictable schedulingCannot use if rate dropped mid-year
Federal Poverty LineFPL for a single personHigh-turnover or complex workforcesMay require lowest employee contribution

What Happens When a Health Plan Fails the Affordability Test?

When a plan fails the ACA affordability test, the consequences fall under Section 4980H(b) of the Internal Revenue Code — sometimes called the “B Penalty” or the “affordability penalty.” An employer is only exposed to this penalty if at least one full-time employee receives a premium tax credit (PTC) through a Marketplace plan. The IRS does not automatically assess the penalty — it is triggered by employee Marketplace enrollments and the subsequent IRS matching process.

How the ESRP Penalty Is Calculated

The 4980H(b) ESRP is assessed monthly, per full-time employee who actually receives a PTC through the Exchange. The penalty amount is set by the IRS and adjusted annually — confirm the current dollar figure for 2026 on IRS.gov. The key distinction from the 4980H(a) penalty (for failing to offer coverage at all) is that the (b) penalty only applies to employees who actually go to the Marketplace and receive a subsidy — not to your entire workforce. That said, even a handful of employees triggering PTC claims can result in tens of thousands of dollars in annual exposure for a mid-size employer.

The IRS Notification Process

The IRS identifies potential ESRP liability through the ACA information reporting employers file — Forms 1094-C and 1095-C. The agency matches those filings against individual tax returns where employees claimed PTCs, then issues Letter 226-J to employers with proposed ESRP assessments. Employers have a defined window to respond and dispute the proposed assessment. Accurate, timely 1094-C/1095-C filing is your first line of defense — errors or missing data make it harder to challenge an incorrect penalty notice.

How a PEO Can Take ACA Compliance Off Your Plate

For employers near or over the 50-FTE threshold, ACA tracking, safe harbor calculations, and 1094-C/1095-C reporting represent a significant administrative burden — especially if your workforce includes a mix of full-time, part-time, and variable-hour employees. This is one area where a Professional Employer Organization (PEO) delivers measurable value beyond payroll processing.

A PEO takes on co-employer responsibilities for your workforce, which typically includes managing ACA measurement periods, running affordability calculations, and filing ACA reporting on your behalf. In our experience matching hundreds of businesses through PEO Marketplace, ACA compliance administration is one of the top three reasons employers in the 40–100 FTE range decide to move to a PEO. According to NAPEO, businesses that use a PEO grow 7–9% faster and have 10–14% lower employee turnover than comparable companies that do not — and reduced compliance risk is a core driver of that outcome.

If you are evaluating PEO options, it is worth understanding how different providers handle ACA reporting as part of their service model. Some fully absorb it; others treat it as an add-on. Our guide to the best PEOs for small business breaks down what to look for. You can also review our Insperity cost comparison to see how one of the larger PEOs structures its compliance services relative to competitors.

What to Ask a PEO About ACA Before You Sign

Not all PEOs handle ACA the same way. Before committing, ask specifically: Does the PEO file 1094-C and 1095-C under their own EIN or yours? Who runs the measurement period tracking for variable-hour employees? What happens if an affordability calculation error results in a penalty — who bears that liability? The answers to these questions will tell you a lot about how serious a given provider is about ACA compliance versus treating it as a checkbox.

2026 ACA Affordability: Key Takeaways for Employers

ACA affordability in 2026 comes down to a clear framework: know your IRS threshold percentage (confirm it at IRS.gov), choose the right safe harbor for each employee class, price your lowest-cost plan accordingly, and file accurate 1094-C/1095-C reports on time. If you are managing this manually across a workforce of 50 or more employees, the administrative complexity compounds quickly — especially when you layer in variable-hour workers, seasonal staff, and mid-year new hires.

Whether you handle ACA compliance in-house or explore a PEO partnership, the math matters. Use our free PEO cost calculator to see what employers your size are actually paying for HR and benefits administration — including ACA compliance services — so you have a real benchmark before making any decisions.

Ready to stop managing ACA compliance manually?

Book a free 15-minute call with a PEO Marketplace advisor. We will match you with vetted providers that handle ACA tracking, safe harbor calculations, and 1095-C filing — at no cost to you.

Book My Free PEO Consultation →

Not ready to book a call? Get a free Benefits Benchmark Report for your industry — we will email you a breakdown of what companies your size are paying for HR, benefits, and workers comp so you can compare on your own timeline.

Get My Free Benchmark Report →

Frequently Asked Questions About ACA Affordability

What is the ACA affordability percentage for 2026?

The IRS adjusts the ACA affordability percentage annually and publishes it in a revenue procedure each fall. Employers should confirm the exact 2026 figure directly on IRS.gov before calculating employee contributions, as guessing or using a prior-year number can result in a plan that technically fails the test.

Does the affordability test apply to dependent or family coverage?

No — the ACA affordability test applies only to the employee’s required contribution for self-only coverage, not to the cost of adding dependents or a spouse. However, starting in 2025, the “family glitch” fix from the IRS means dependents’ eligibility for Marketplace tax credits is also affected by the affordability of family-tier coverage, which is a separate but related compliance consideration.

Can I use different safe harbors for different groups of employees?

Yes, employers may use different safe harbors for different employee classifications — for example, the rate of pay safe harbor for hourly workers and the W-2 safe harbor for salaried employees. The IRS requires that each safe harbor be applied consistently to all employees within a reasonable classification, so document your methodology clearly for each group.

What is Form 1095-C and who needs to file it?

Form 1095-C is the ACA information return that Applicable Large Employers must furnish to full-time employees and file with the IRS alongside Form 1094-C. It reports whether coverage was offered, the employee’s required contribution, and the safe harbor code used — this is the data the IRS uses to identify potential ESRP liability. ALEs must file these forms annually, with deadlines set by the IRS for each reporting year.

Does a PEO file ACA forms on my behalf?

Many PEOs do file Forms 1094-C and 1095-C as part of their co-employment service, though the specific arrangement varies by provider — some file under their own EIN, others file under the client employer’s EIN. Before selecting a PEO, confirm exactly who bears filing responsibility and what liability the PEO accepts if an error leads to a proposed ESRP assessment. Our comparison of leading PEOs covers how different providers approach this.
The Short Answer

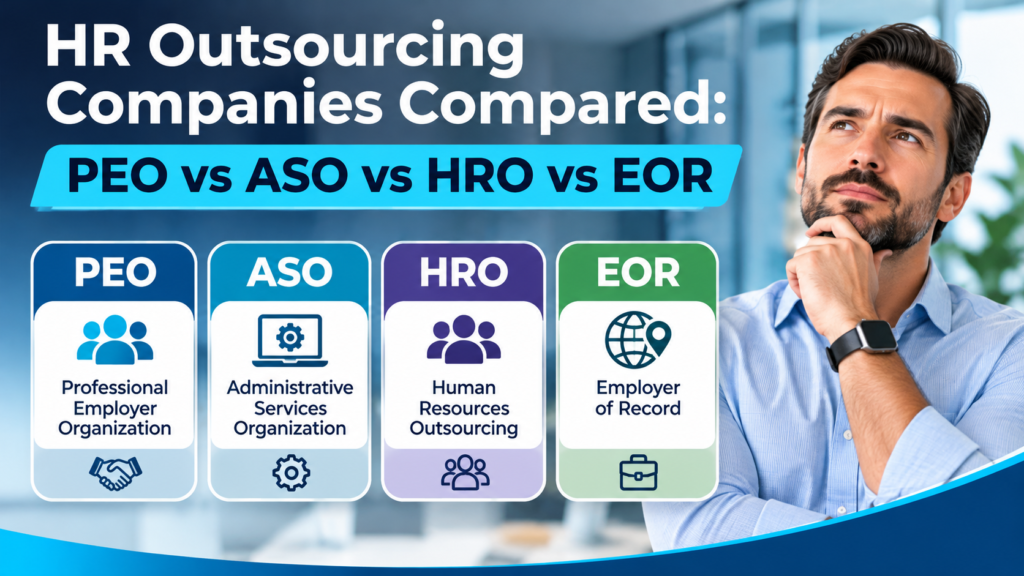
When comparing HR outsourcing companies, there are four primary models: PEO (Professional Employer Organization), ASO (Administrative Services Organization), HRO (Human Resources Outsourcing), and EOR (Employer of Record). Each model differs in who holds employer liability, what services are bundled, and how pricing is structured. Choosing the wrong model means paying for services you do not need or missing protections you do.

Why the Model You Choose Matters More Than the Vendor

Most business owners shopping for HR help start by comparing vendors — Gusto vs. Rippling, Insperity vs. TriNet. That is the wrong starting point. The model determines your legal exposure, your cost structure, and whether you can actually get the HR support your business needs at your stage of growth.

Based on our analysis of 40+ vetted PEOs and the businesses that work with them, the most common and costly mistake is selecting a model that fits a vendor’s sales pitch rather than the company’s actual risk profile and HR workload. This guide lays out the four models with no slant toward any one of them.

According to NAPEO, more than 500 PEOs operate in the United States, covering roughly 4 million worksite employees — but PEOs represent just one of several outsourcing structures worth evaluating.

Comparing PEOs is easier when you know your baseline cost. The PEO Calculator shows what a PEO would cost for your company in 60 seconds, with no call needed.

Try the PEO Calculator →

What Is a PEO (Professional Employer Organization)?

A PEO enters a co-employment relationship with your business. Your employees remain yours day-to-day, but the PEO becomes the employer of record for tax and benefits purposes. This means payroll taxes are filed under the PEO’s Employer Identification Number, and employees gain access to the PEO’s large-group benefit plans.

Who Holds Employer Liability in a PEO

Liability is shared. The PEO assumes responsibility for payroll tax compliance, benefits administration, and many HR compliance risks. You retain control over hiring, firing, and day-to-day management. This shared liability model is what distinguishes a PEO from every other outsourcing structure.

What Is Included in a PEO

  • Payroll processing and tax filing under the PEO’s EIN
  • Large-group health, dental, vision, and ancillary benefits
  • Workers compensation coverage and claims management
  • HR compliance support and employee handbook assistance
  • Dedicated HR support (varies by provider)
  • Access to 401(k) and other retirement plans

PEO Pricing Structure

PEOs typically charge either a percentage of gross payroll (most common, usually 2–6%) or a flat per-employee-per-month (PEPM) fee ranging from $80 to $200+. Benefits premiums are often separate. You can get a baseline number for your headcount and payroll using the PEO Calculator.

Ideal Company Profile for a PEO

PEOs deliver the most value for businesses with 5–250 employees that want to offer competitive benefits without paying large-group premiums on their own, need compliance infrastructure without hiring a full HR department, and are willing to operate within the PEO’s benefit plan structure. According to NAPEO, PEO clients grow 7–9% faster and have 10–14% lower employee turnover than companies not using a PEO.

What Is an ASO (Administrative Services Organization)?

An ASO provides the same administrative HR services as a PEO — payroll, compliance support, benefits administration — but without co-employment. You remain the sole employer of record. The ASO works as a service vendor, not a legal co-employer.

Who Holds Employer Liability in an ASO

You do. The ASO processes payroll and manages HR tasks on your behalf, but all employer tax liabilities, workers compensation obligations, and compliance risks stay with your business. The ASO does not absorb any legal employer risk.

What Is Included in an ASO

  • Payroll processing under your EIN
  • Benefits administration (you source and own the plans)
  • HR compliance guidance and document management
  • Employee self-service technology platforms
  • Onboarding and offboarding support

ASO Pricing Structure

ASOs typically charge a flat PEPM fee ($20–$80 depending on service scope) or a percentage of payroll. Because you source your own benefits separately, the total cost of an ASO arrangement plus standalone benefits is often higher than a comparable PEO — especially for smaller companies that cannot negotiate group rates.

Ideal Company Profile for an ASO

ASOs work best for mid-size businesses (100+ employees) that already have competitive benefits in place, have an internal HR team that needs administrative support rather than strategic guidance, and want to retain full control over benefits plan design without joining a PEO’s master plan.

What Is an HRO (Human Resources Outsourcing)?

HRO is the broadest and most flexible category. It refers to outsourcing specific HR functions — recruiting, training, performance management, benefits consulting, compliance audits — to one or more specialized vendors. Unlike PEOs and ASOs, HRO is not a single bundled relationship; it is a menu of services assembled to fill gaps in an internal HR operation.

Who Holds Employer Liability in an HRO

You retain all employer liability. HRO vendors provide expertise and execution on defined deliverables. They do not assume any co-employment relationship or statutory employer obligations.

What Is Included in an HRO

  • Recruiting and talent acquisition (RPO)
  • Learning and development program delivery
  • Benefits consulting and broker services
  • HR technology implementation and support
  • Compliance auditing and policy development
  • Compensation benchmarking and total rewards design

HRO Pricing Structure

HRO pricing varies widely by function. Recruiting RPO engagements may be fee-per-hire or monthly retainer. Benefits consulting is often project-based or commission-based through broker relationships. Technology platforms charge PEPM fees. The total investment depends entirely on which functions are outsourced and at what scope.

Ideal Company Profile for an HRO

HRO is the right model for larger companies (250+ employees) with an established internal HR team that needs specialized support for specific functions, or for companies undergoing rapid growth that need recruiting or training capacity without permanent headcount. It is not efficient for small businesses that need broad HR coverage — the administrative overhead of managing multiple vendors quickly outweighs the flexibility.

What Is an EOR (Employer of Record)?

An EOR becomes the legal employer of your workers in a specific jurisdiction — most commonly used when hiring internationally or in states where you lack a legal entity. The EOR handles all local employment law compliance, payroll, taxes, and statutory benefits on your behalf. You direct the work; the EOR owns the employment relationship on paper.

Who Holds Employer Liability in an EOR

The EOR holds full employer liability in that jurisdiction. This is the most complete transfer of employer risk of any model — which also means less control over local benefits and employment terms than you would have with a local entity.

What Is Included in an EOR

  • Legal entity in the target country or state
  • Local payroll processing and tax remittance
  • Statutory benefits compliance (health, leave, pension per local law)
  • Employment contracts drafted to local standards
  • Termination and offboarding in compliance with local law

EOR Pricing Structure

EOR providers typically charge $500–$2,000+ per employee per month depending on the country, local complexity, and service tier. Pricing is notably higher than domestic HR outsourcing because the EOR is absorbing full legal employer risk in a foreign or unfamiliar jurisdiction.

Ideal Company Profile for an EOR

EORs are purpose-built for companies expanding internationally without establishing a local entity, or hiring a small number of remote workers in states where they have no payroll registration. For domestic multi-state hiring at scale, the per-employee cost of an EOR usually makes a PEO the more economical option. The IRS guidance on employer identification provides useful context on EIN responsibilities that an EOR assumes on your behalf.

Side-by-Side Comparison: PEO vs ASO vs HRO vs EOR

FeaturePEOASOHROEOR
Co-employmentYesNoNoYes (full)
Employer liabilitySharedClient onlyClient onlyEOR only
Payroll EINPEO’s EINYour EINYour EINEOR’s EIN
Benefits accessLarge-group plansYour own plansConsulting onlyStatutory only
Typical pricing2–6% payroll or $80–$200 PEPM$20–$80 PEPMVariable by function$500–$2,000+ PEPM
Best employee count5–250100+250+1–50 (international)
Workers comp includedYesNoNoYes (local)
Use caseSMB full HR stackAdmin support, own benefitsFill specific HR gapsInternational or remote hiring

How to Choose the Right HR Outsourcing Model

The right model depends on three variables: how many employees you have, how much employer liability you want to transfer, and whether benefits access is a strategic priority.

Choose a PEO if

You have 5–250 employees, want to offer Fortune 500-caliber benefits without self-insuring, and need broad HR compliance coverage without building an internal HR team. Businesses that want to save 20–40% on operational and benefit costs compared to managing benefits independently often find the PEO model the most cost-efficient path at this size. See how leading PEOs for small businesses compare on this criteria.

Choose an ASO if

You already have strong benefits in place, want to keep your own EIN and benefit plan design, and simply need better HR technology and administrative support. This is common for mid-size companies that have outgrown startup-era HR tools but are not ready for the co-employment structure a PEO requires.

Choose HRO if

You have an internal HR team and need to outsource specific, high-skill functions — talent acquisition, compensation benchmarking, or compliance auditing — without touching your core employer structure. The Department of Labor’s compliance assistance resources can help you identify which compliance gaps are most common at your size before engaging an HRO.

Choose an EOR if

You are hiring workers in countries or states where you have no legal entity and want zero exposure to local employment law complexity. EOR is a bridge solution, not a permanent infrastructure — most companies eventually establish their own entity once headcount in a region justifies it.

A Note on Hybrid Arrangements

Some providers offer combinations. A PEO may also offer EOR services for international contractors. An HRO vendor may bundle ASO-style payroll administration. In our experience matching hundreds of businesses with HR solutions, hybrid arrangements often signal that a provider is trying to cover a broader market rather than delivering specialized depth. Evaluate what you actually need before accepting a bundled offer that includes services you will not use.

If you are specifically evaluating PEO vendors side by side, the Gusto vs. Justworks comparison and the Insperity cost breakdown are useful starting points for understanding how pricing and service scope differ across named providers.

Next Steps

If you have identified the right model and want to compare specific providers within it, PEO Marketplace works with 40+ vetted PEOs and can match your business to the best-fit options based on your industry, headcount, and benefits priorities — without a sales push toward any single vendor.

Schedule a Matching Consultation →

Prefer to compare on your own timeline first. Run the Benefits Benchmark for your industry and we will email you a breakdown of what companies your size are paying for HR, benefits and workers comp.

Run the Benefits Benchmark →

Frequently Asked Questions

What is the difference between a PEO and an EOR?

A PEO enters a co-employment arrangement where employer liability is shared between the PEO and your business, and your employees are filed under the PEO’s EIN for payroll and benefits purposes. An EOR becomes the full legal employer in a specific jurisdiction, typically used for international or remote hires where you have no registered entity — the EOR assumes all local employer liability, not just a share of it.

Is a PEO or an ASO better for a small business?

For most businesses under 100 employees, a PEO delivers more value than an ASO because the co-employment structure unlocks large-group benefit rates that an ASO arrangement cannot access. An ASO makes more sense when you already have established, competitive benefit plans and primarily need administrative support and HR technology.

Does using an EOR mean I give up control of my employees?

An EOR becomes the legal employer on paper, but you retain full control over the work your employees perform, their daily management, and their role within your organization. The EOR’s control is limited to the employment law and payroll compliance side of the relationship in the relevant jurisdiction.

How do I know if my company needs HRO instead of a PEO?

If your business already has an internal HR team and you need to fill specific gaps — such as recruiting capacity, compliance auditing, or leadership training — HRO is likely the better fit because you are buying expertise for defined functions rather than a full HR infrastructure replacement. A PEO is better suited when you need end-to-end HR coverage and do not have a dedicated HR team managing day-to-day needs.

Can a company use more than one HR outsourcing model at the same time?

Yes, and many growing companies do. A common combination is a PEO for domestic employees paired with an EOR for international hires in countries where the company has no legal entity. The key is ensuring the two arrangements do not create conflicting employer-of-record designations for the same employees or jurisdictions.

The seven most common payroll tax mistakes small businesses make are late tax deposits, using the wrong deposit schedule, errors on Form 941, missed state filings, mishandling fringe benefit taxation, worker misclassification, and late or incorrect W-2s. Each one carries a specific IRS penalty structure that compounds fast. Getting even one of these wrong can cost a business thousands of dollars in penalties, interest, and professional fees to clean up.

If you are running payroll yourself or relying on basic software without expert oversight, the risk is higher than most owners realize. This guide walks through each mistake, what the IRS actually charges, and how to protect your business before a notice arrives.

Why Payroll Tax Compliance Is Harder Than It Looks

Payroll tax compliance means accurately calculating, withholding, depositing, and reporting federal and state payroll taxes on the correct schedule — every pay period, without exception. The IRS does not distinguish between honest mistakes and willful violations when it comes to calculating penalties. The Federal Trust Fund Recovery Penalty, outlined on IRS.gov, can hold business owners personally liable for unpaid payroll taxes — even if the business entity itself closes.

According to the IRS, employment tax penalties are among the most frequently assessed against small businesses. The complexity comes from the intersection of federal deposit rules, state agency requirements, quarterly reporting deadlines, and classification rules — all of which change regularly.

Find out whether a PEO makes sense for your business. The PEO Calculator shows you the real cost in 60 seconds, with no call and no commitment.

Try the PEO Calculator →

The 7 Payroll Tax Mistakes That Trigger IRS Penalties

1. Late Tax Deposits

Late payroll tax deposits are the single most common trigger for IRS penalties on small businesses. The IRS assesses a tiered failure-to-deposit penalty that starts at 2% for deposits 1–5 days late and climbs to 15% for amounts still unpaid more than 10 days after a notice is issued. On a $20,000 payroll tax liability, a 10% penalty alone is $2,000 — before interest accrues.

Deposits must be made through the Electronic Federal Tax Payment System (EFTPS). Wire transfers or checks sent to the IRS do not count as timely deposits. Many owners using basic payroll software assume the software is handling deposits automatically when it is not configured to do so, leading to surprise penalties months later.

2. Using the Wrong Deposit Schedule

The IRS assigns businesses either a monthly or semi-weekly deposit schedule based on the total taxes reported during a lookback period — the 12-month period ending June 30 of the prior year. If your total employment tax liability during that period was $50,000 or less, you deposit monthly. If it exceeded $50,000, you must deposit semi-weekly.

Businesses that grow quickly often miss the transition from monthly to semi-weekly depositor status. Depositing on a monthly schedule when semi-weekly is required results in late-deposit penalties on every paycheck cycle. The IRS publishes the deposit schedule rules in Publication 15 (Circular E), and reviewing it at the start of each calendar year is essential.

3. Form 941 Errors

Form 941 is the quarterly payroll tax return that reconciles your deposits against what you owe in federal income tax withholding, Social Security, and Medicare taxes. Common errors include transposed employee counts, math errors in tax calculations, missing signatures, and failing to account for mid-quarter hires or terminations.

An inaccurate Form 941 can trigger a discrepancy notice, force a manual reconciliation process, and generate interest charges on any understated balance. The IRS failure-to-file penalty for Form 941 is 5% of the unpaid tax for each month or partial month the return is late, up to 25%. Even a minor math error can flag your account for additional scrutiny.

4. Missed or Late State Payroll Tax Filings

Federal compliance is only half the equation. Every state with an income tax has its own withholding deposit schedules, quarterly or annual reconciliation returns, and unemployment insurance (SUI) filings. Some states also require local income tax withholding depending on where employees work — not where the business is headquartered.

Remote work has made this significantly more complicated. An employee working from a different state than your business address may create nexus in that state, triggering new registration, withholding, and filing obligations. Missing a state filing carries its own penalty structure independent of the IRS, and in some states, the penalties exceed federal rates. The Department of Labor’s unemployment insurance page is a useful starting point for understanding state-level SUI obligations.

5. Mishandling Fringe Benefit Taxation

Fringe benefits that are not properly excluded under IRS rules are taxable wages and must be included in payroll. Common examples include personal use of a company vehicle, employer-paid life insurance over $50,000, non-qualifying moving expense reimbursements, and certain gifts or awards above the de minimis threshold.

Many small business owners either omit taxable fringe benefits from payroll entirely or assume all benefits are tax-exempt. When these amounts are not included in taxable wages, the business underpays FICA taxes and income tax withholding, which triggers both deposit penalties and potential reclassification of the benefit as compensation during an audit. IRS Publication 15-B covers the rules for fringe benefit exclusions in detail.

6. Worker Misclassification

Classifying an employee as an independent contractor to avoid payroll taxes is one of the highest-risk payroll errors a business can make. The IRS uses a multi-factor behavioral and financial control test to determine whether a worker is truly an independent contractor. When misclassification is found, the business becomes liable for the employer’s share of FICA taxes, the employee’s share that should have been withheld, federal income tax withholding, and applicable penalties and interest — often covering multiple tax years simultaneously.

The IRS Voluntary Classification Settlement Program (VCSP) allows businesses to proactively reclassify workers and pay a reduced penalty, but only before an audit begins. The VCSP details are available on IRS.gov. If a misclassification issue is discovered during an audit, the full penalty structure applies with no reduction option.

7. Late or Incorrect W-2s

W-2s must be furnished to employees by January 31 and filed with the Social Security Administration by the same date. The penalty for failure to file a correct W-2 by the deadline ranges from $60 to $310 per form for 2026, depending on how late the filing is and whether the error was due to intentional disregard. For a business with 25 employees that files W-2s even 30 days late, the penalty exposure can reach $4,650 or more.

Common W-2 errors include incorrect Social Security numbers, wrong employer EIN, missing Box 12 codes for deferred compensation or health coverage, and totals that do not reconcile with quarterly Form 941 submissions. These discrepancies flag your account with both the IRS and SSA, often leading to notices and additional back-and-forth that consumes significant time.

How Payroll Complexity Compounds Over Time

Each of these seven mistakes is solvable in isolation. The real danger is that they tend to compound. A business that misclassifies a worker may also be omitting their fringe benefits from payroll, depositing on the wrong schedule, and missing state filings for the states where those workers operate. When the IRS opens an examination, all of these issues surface together.

According to data from NAPEO, businesses that outsource HR and payroll functions through a professional employer organization spend significantly less time on administrative compliance and report fewer penalty events. Based on our analysis of 40+ vetted PEOs, one of the most consistent reasons business owners move to a structured HR solution is specifically to transfer payroll tax filing responsibility away from themselves or an overloaded office manager.

How a PEO Transfers Payroll Tax Filing Responsibility

A Professional Employer Organization (PEO) enters into a co-employment arrangement with your business. In that arrangement, the PEO becomes the employer of record for tax purposes and assumes responsibility for calculating, depositing, and filing your federal and state payroll taxes — including Form 941, W-2s, and state unemployment returns.

This is not just administrative convenience. Under a PEO relationship, the PEO’s EIN is used for tax filings, and the PEO carries the compliance burden and infrastructure to stay current on deposit schedules, state registration requirements, and fringe benefit classification rules. For small businesses that lack a dedicated payroll tax specialist, this transfer of responsibility eliminates the exposure points outlined above.

Businesses working with PEOs also gain access to group-rate benefits purchasing power. According to NAPEO, PEO clients grow 7–9% faster and have 10–14% lower employee turnover than comparable businesses. The compliance infrastructure is a core component of that advantage. If you are evaluating whether a PEO is the right fit, the guide to best PEOs for small businesses breaks down the options by company size and industry.

It is worth noting that not all PEOs handle payroll tax filing identically. Some PEOs file under their own EIN (fully assuming the tax responsibility), while others file under your EIN with shared responsibility. When comparing options, ask specifically how payroll tax deposits and employer filings are handled. The comparison of Gusto and Justworks is a useful reference for understanding how smaller PEO-adjacent platforms differ from full-service PEO arrangements on this dimension.

Steps to Reduce Payroll Tax Risk Right Now

Whether or not you ultimately move to a PEO, the following steps reduce your exposure to the penalties described above.

  • Confirm your deposit schedule at the start of each year by reviewing your lookback period liability against the IRS threshold.
  • Enroll in and actively use EFTPS for all federal payroll tax deposits. Do not rely on a software platform to do this without verifying that it is configured correctly.
  • Reconcile Form 941 to your payroll register before submitting each quarter. Total wages, withholding amounts, and employee counts should match exactly.
  • Audit worker classification annually, particularly for contractors who work exclusively for your business or who work on-site under your direction.
  • Map your state filing obligations against where employees physically work, not just where they were hired from.
  • Include taxable fringe benefits in payroll at the time they are provided, not at year-end when corrections become more complex.
  • Set a W-2 preparation deadline of January 15 internally so that errors can be corrected before the January 31 statutory deadline.

If you are unsure where your current process stands, the PEO matching service at PEO Marketplace can connect you with vetted providers who specialize in taking on exactly this kind of compliance responsibility for businesses your size.

What It Costs to Get This Wrong

MistakeIRS Penalty RangeAdditional Exposure
Late deposit2%–15% of deposit amountInterest on unpaid balance
Wrong deposit schedule2%–15% per periodCompounds each pay cycle
Form 941 errors / late filing5% per month, up to 25%IRS notice and audit risk
Missed state filingsVaries by stateState interest + possible liens
Fringe benefit omissionFICA underpayment penaltiesBack taxes + gross-up calculations
Worker misclassificationFull FICA + income tax + penaltiesPersonal liability via TFRP
Late or incorrect W-2s$60–$310 per formSSA discrepancy notices

Frequently Asked Questions

What is the IRS penalty for late payroll tax deposits?

The IRS assesses a failure-to-deposit penalty ranging from 2% for deposits 1–5 days late to 15% for amounts still unpaid more than 10 days after an IRS notice is issued. Interest accrues separately on top of the penalty until the balance is paid in full.

How does the IRS determine worker classification?

The IRS uses a behavioral control, financial control, and type-of-relationship test to determine whether a worker is an employee or independent contractor. Workers who are directed on how, when, and where to work, and who rely on the business as their primary source of income, are typically classified as employees regardless of contract language.

What happens if a small business misses a state payroll tax filing?

Missing a state payroll tax filing triggers state-specific penalties and interest that accrue independently of any federal issues. In some states, repeated missed filings can result in a tax lien against business assets or personal assets of the responsible owner or officer.

Can a PEO completely eliminate payroll tax penalty risk?

When a PEO files payroll taxes under its own EIN as the employer of record, it assumes the primary filing responsibility and significantly reduces the client business’s direct penalty exposure. The business still has an obligation to provide accurate payroll data to the PEO on time, so the risk is shared rather than entirely eliminated.

What is the Trust Fund Recovery Penalty and who does it apply to?

The Trust Fund Recovery Penalty (TFRP) allows the IRS to hold individual business owners, officers, or other responsible parties personally liable for unpaid payroll taxes — specifically the employee portion of Social Security and Medicare taxes and withheld income tax. It applies when the IRS determines that a responsible person willfully failed to collect or pay over those taxes, and it can survive business closure or bankruptcy.

If you want to understand what handing off payroll tax compliance to a vetted provider would actually cost for your business, a conversation with the team at PEO Marketplace takes less than 30 minutes and covers your specific headcount, state footprint, and industry. Schedule a time below.

Talk to a PEO matching specialist at PEO Marketplace

Based on our analysis of 40+ vetted PEOs, we match your business with providers that fit your size, state footprint, and compliance needs — with no pressure and no cost to you.

Schedule a Consultation →

Prefer to compare on your own timeline first. Run the Benefits Benchmark for your industry and we will email you a breakdown of what companies your size are paying for HR, benefits and workers comp.

Run the Benefits Benchmark →

The 2027 HSA limits are now official. Per IRS Revenue Procedure 2026-24, employees can contribute up to $4,500 for self-only HDHP coverage and $9,000 for family coverage in plan year 2027. If your business sponsors a high-deductible health plan, every figure in this article has a direct impact on your payroll configuration, plan documents, and what you tell employees before open enrollment.

What Are the 2027 HSA Limits?

The 2027 HSA limits set by the IRS are $4,500 for self-only coverage, $9,000 for family coverage, and a $1,000 catch-up contribution for account holders age 55 and older — all sourced directly from IRS Rev. Proc. 2026-24. These are the maximum amounts an individual can contribute to a Health Savings Account in calendar year 2027, combining both employee and employer contributions.

2027 HSA Contribution Limits at a Glance

Coverage Type2026 Limit2027 LimitChange
Self-Only$4,300$4,500+$200
Family$8,550$9,000+$450
Catch-Up (age 55+)$1,000$1,000No change

Source: IRS Rev. Proc. 2026-24. 2026 figures included for reference; confirm prior-year plan documents against your plan administrator records.

What Are the 2027 HDHP Minimum Deductibles and Out-of-Pocket Maximums?

To qualify for HSA contributions, a health plan must meet IRS thresholds for minimum deductibles and maximum out-of-pocket costs. For plan year 2027, those thresholds are set by IRS Rev. Proc. 2026-24 and are listed below.

2027 HDHP Thresholds

HDHP ThresholdSelf-OnlyFamily
Minimum Deductible$1,750$3,500
Out-of-Pocket Maximum$8,700$17,400

Source: IRS Rev. Proc. 2026-24. A plan whose deductible falls below these minimums disqualifies employees from making HSA contributions entirely.

Employers should verify that their carrier has updated plan design documents to reflect these minimums before the first day of the 2027 plan year. If your HDHP deductible is set below the minimum, employees enrolled in that plan cannot legally contribute to an HSA, which creates compliance exposure and employee relations issues during tax season.

Find out whether a PEO makes sense for your business. The PEO Calculator shows you the real cost in 60 seconds, with no call and no commitment.

Try the PEO Calculator →

What Changed in the 2027 Excepted Benefit HRA Limit?

The excepted benefit HRA (EBHRA) limit for 2027 is $2,250, as set in IRS Rev. Proc. 2026-24. This is the maximum an employer can contribute to an excepted benefit HRA — a standalone HRA that covers limited benefits such as dental and vision — without disqualifying employees from HSA eligibility.

Excepted benefit HRAs are a separate product from HDHP-linked HSA plans, but many small employers offer both. If you contribute more than $2,250 to an EBHRA in 2027, the account loses its excepted benefit status, which can affect employees’ ability to fund their HSAs. Work with your plan administrator or benefits counsel to confirm your EBHRA contribution amounts are within the updated limit.

How Do the 2027 HSA Limits Affect Payroll Configuration?

Payroll systems need to be updated to enforce the new 2027 HSA contribution limits before the first payroll run of the plan year. Most payroll platforms allow you to set annual HSA caps per employee tier — self-only versus family — and the system will reject contributions that would push an employee over the annual limit.

Payroll Update Checklist for 2027

  • Update the self-only HSA cap to $4,500
  • Update the family HSA cap to $9,000
  • Confirm catch-up contribution eligibility flags for employees turning 55 in 2027
  • Adjust employer contribution amounts if your strategy is a fixed dollar match or a percentage of the IRS maximum
  • Verify that your payroll system treats employer and employee contributions as combined toward the annual cap
  • Run a test payroll cycle before the plan year starts to catch configuration errors

According to the IRS Publication 969, the annual HSA contribution limit applies to the combined total of employer and employee contributions. If your business contributes $1,000 toward a self-only employee’s HSA, that employee can contribute a maximum of $3,500 on their own in 2027.

What Plan Document Updates Are Required for 2027?

Plan documents, summary plan descriptions (SPDs), and open enrollment materials must reflect the updated 2027 HSA limits and HDHP thresholds before the plan year begins. Failing to update these documents is a compliance violation under ERISA and can expose the plan to penalties.

Documents to Update Before the 2027 Plan Year

  • Summary Plan Description (SPD): Must reflect the new deductible minimums, out-of-pocket maximums, and contribution limits
  • HSA custodian agreement: Confirm your HSA administrator has updated annual contribution limits in their system
  • Section 125 / Cafeteria Plan document: If employees fund HSA contributions through payroll deferrals, the cafeteria plan document must be updated
  • Open enrollment materials: Any brochure, portal page, or enrollment guide showing HSA limits must be revised
  • Employee benefit statements: Year-end statements and benefits summaries sent to employees should use 2027 figures

How Should Employers Set Their 2027 HSA Contribution Strategy?

The right employer HSA contribution strategy depends on your workforce demographics, benefits budget, and competitive positioning — not just the IRS maximums. That said, the 2027 limit increases create a natural opportunity to review whether your current employer contribution level still makes sense.

Common Employer Contribution Models

Based on our analysis of 40+ vetted PEOs and their client benefit structures, most small and mid-size employers use one of three approaches:

  • Flat dollar seed: A fixed amount per employee tier — for example, $600 for self-only and $1,200 for family — regardless of the IRS maximum. Simple to administer and predictable in cost.
  • Percentage of limit: A set percentage of the annual IRS maximum. As limits rise, your contribution rises proportionally. This approach signals to employees that the benefit scales with inflation.
  • Half the deductible: Contributing an amount equal to half the HDHP minimum deductible. For 2027, that would be $875 for self-only ($1,750 ÷ 2) and $1,750 for family ($3,500 ÷ 2). This approach frames the employer contribution as deductible protection.

Employers competing for talent in tight labor markets may want to benchmark their HSA contributions against peers. Our Benefits Benchmark tool shows what companies your size in your industry are contributing to health benefits, including HSA seeding.

How Can a PEO Help Manage 2027 HSA Compliance?

A Professional Employer Organization (PEO) takes on shared employer responsibilities including benefits administration, payroll configuration, and plan document compliance. For small employers without a dedicated HR team, a PEO is one of the most practical ways to ensure the 2027 HSA limits are reflected correctly across every system before the plan year starts.

PEOs typically access large-group health insurance markets on behalf of their clients, which means employees at a 15-person company may qualify for HDHP plan designs and HSA pairing options that would not be available on the small-group market. According to NAPEO, businesses that use a PEO grow 7–9% faster and have 10–14% lower employee turnover than comparable non-PEO businesses. Many employers working with a PEO also see 20–40% reductions in operation and benefit costs when moving from a traditional broker arrangement.

If you are evaluating PEO options, see how the leading platforms compare in our guide to the best PEOs for small businesses, or review a detailed cost breakdown in our Insperity cost comparison.

How Should Employers Communicate 2027 HSA Limit Changes to Employees?

Employees need clear, timely communication about the 2027 HSA limits so they can adjust their annual contribution elections before the plan year begins. Waiting until open enrollment materials go live is often too late for employees who are planning their household budgets.

Employee Communication Timeline

  • 60–90 days before plan year start: Send a preview email or benefits newsletter summarizing the new limits and what changed from 2026
  • Open enrollment window: Include a one-page HSA fact sheet in enrollment packets with the new maximums, the employer contribution amount, and instructions for updating payroll deferrals
  • Post-enrollment confirmation: Send employees a confirmation of their elected HSA contribution alongside their HDHP plan enrollment confirmation
  • January payroll statement: First pay stub of 2027 should clearly show the HSA deduction amount so employees can verify their elections took effect correctly

Employees age 55 and older often overlook the $1,000 catch-up contribution. A targeted reminder for this group — particularly in companies with an aging workforce — can meaningfully improve employee satisfaction with the benefits package at no additional administrative cost.

Frequently Asked Questions

What are the 2027 HSA contribution limits?

The 2027 HSA contribution limits are $4,500 for self-only HDHP coverage and $9,000 for family HDHP coverage, per IRS Rev. Proc. 2026-24. Individuals age 55 or older may contribute an additional $1,000 as a catch-up contribution, bringing their maximums to $5,500 and $10,000 respectively.

What are the 2027 HDHP minimum deductibles?

For plan year 2027, a health plan must have a minimum deductible of $1,750 for self-only coverage or $3,500 for family coverage to qualify as an HDHP under IRS rules. Plans with deductibles below these thresholds do not qualify, and employees enrolled in them cannot make HSA contributions.

Do employer HSA contributions count toward the 2027 limit?

Yes. The IRS annual HSA contribution limit applies to the combined total of both employer and employee contributions. If an employer contributes $1,000 to a self-only employee’s HSA in 2027, that employee can contribute no more than $3,500 on their own before hitting the $4,500 annual cap.

When do payroll systems need to be updated for the 2027 HSA limits?

Payroll systems should be updated to reflect the 2027 HSA limits before the first payroll run of the new plan year. Running the first payroll with outdated caps can result in over-contributions that require corrective distributions, which creates taxable income for affected employees and administrative burden for the employer.

Is the excepted benefit HRA limit changing for 2027?

Yes. The excepted benefit HRA limit for 2027 is $2,250, as published in IRS Rev. Proc. 2026-24. Employers who contribute more than $2,250 to an EBHRA in 2027 risk disqualifying that account’s excepted benefit status, which can affect enrolled employees’ ability to fund an HSA.


Ready to review your 2027 benefits strategy with an expert.

Schedule a complimentary consultation with the PEO Marketplace team. We work with 40+ vetted PEOs and can show you several options side by side so you have the full picture before making a decision.

Schedule a Consultation →

Prefer to compare on your own timeline first. Run the Benefits Benchmark for your industry and we will email you a breakdown of what companies your size are paying for HR, benefits and workers comp.

Run the Benefits Benchmark →

Health Net is leaving California’s commercial group market entirely by February 28, 2027. All small-group and large-group medical, dental, and vision plans through Health Net of California, Inc. and Health Net Life Insurance Company will terminate on that date, including groups that renew before then. If your business currently carries Health Net coverage, you have a firm deadline and a real transition to manage.

Notices began arriving September 1, 2026, so many California employers are already in the middle of this. This guide lays out the timeline, your replacement options, and the steps to take so your employees do not experience a gap in coverage or lose access to their current providers.

What Does Health Net Leaving California Mean for Your Group Plan?

Health Net’s exit means every California commercial group policy it currently carries — medical, dental, and vision — ends on February 28, 2027, with no renewal path on the same carrier. This is a forced move, not an optional one. Groups that renew before the deadline will still be terminated at February 28, 2027, so an early renewal does not extend coverage beyond that date.

Health Net of California, Inc. and Health Net Life Insurance Company are both included in the exit, so there is no sister entity to roll into. The exit covers the small-group market (1–100 employees) and large-group accounts alike. Your broker or benefits administrator should have received formal notice beginning September 1, 2026, per Health Net’s exit communications and reporting by Venbrook on September 10, 2026.

The practical implication: every affected employer needs a replacement carrier bound and effective no later than March 1, 2027. Given open enrollment cycles, underwriting timelines, and the volume of groups simultaneously shopping the California market, most advisors are recommending employers begin comparing options by Q4 2026 at the latest.

Run the numbers on better benefits for your team. The PEO Calculator shows what companies your size are paying.

Try the PEO Calculator →

What Is the Hard Deadline and Key Timeline?

February 28, 2027 is the last day Health Net group coverage is active in California. No exceptions have been announced for any group size or plan type.

  • September 1, 2026: Health Net begins issuing termination notices to groups and brokers (Health Net exit page; Venbrook, Sept 10, 2026).
  • Q4 2026: Recommended window to begin formal carrier comparisons and collect employee census data for quoting.
  • January–February 2027: Target window for binding new coverage so ID cards and network access are in place before March 1.
  • February 28, 2027: All Health Net of California commercial group medical, dental, and vision coverage terminates.
  • March 1, 2027: New coverage must be active to avoid any lapse.

One timing risk worth flagging: California’s group market will see an unusually high volume of employers shopping simultaneously. Carriers and underwriters may slow down. Starting early gives you leverage and options; waiting until January 2027 may limit both.

What Replacement Options Should California Employers Compare?

California employers moving off Health Net have several credible paths, and the right one depends on your group size, budget, provider preferences, and risk tolerance. Here is a structured comparison of the main alternatives.

Fully Insured Group Plans Through a New Carrier

This is the most direct replacement path. California carriers in the small-group and large-group space include Anthem Blue Cross, Blue Shield of California, Kaiser Permanente, Cigna, and UnitedHealthcare, among others. Each maintains distinct provider networks, so network overlap with your employees’ current physicians is the first filter to apply.

Key considerations:

  • Confirm whether current specialists and hospitals are in-network under the new carrier’s California HMO or PPO plans.
  • Compare out-of-pocket maximums for 2027. The IRS has published HSA-compatible HDHP out-of-pocket limits for 2027; confirm current figures at IRS.gov as 2027 figures are released.
  • Ask about continuity-of-care provisions if an employee is mid-treatment — California law provides some protections, but the specifics depend on the new carrier’s policy.

Level-Funded Plans

Level-funded plans sit between fully insured and self-funded arrangements. Your company pays a fixed monthly amount that covers expected claims, stop-loss insurance, and administration. If claims come in lower than projected, you may receive a refund of the surplus. For groups of 10–100 employees with generally healthy workforces, level-funded plans can deliver meaningful cost advantages and richer plan designs compared to standard fully insured small-group options.

Carriers offering level-funded products in California include Blue Shield of California, Cigna, and several regional carriers. Because underwriting is more individualized, your group’s claims history matters.

ICHRA (Individual Coverage HRA)

An Individual Coverage Health Reimbursement Arrangement allows employers to reimburse employees tax-advantaged for individual market premiums instead of providing a group plan. ICHRA was established under IRS and DOL guidance and allows employers to set a defined monthly reimbursement amount per employee class. Employees then purchase their own coverage through Covered California or directly from a carrier.

ICHRA works well for employers with geographically dispersed employees or those who want cost predictability. For detailed IRS guidance on ICHRA rules, see IRS Notice 2019-45 and subsequent guidance at IRS.gov.

PEO Master Health Plans

A Professional Employer Organization (PEO) co-employs your workforce and pools your employees into a large-group master health plan. Because PEOs aggregate thousands of employees across many client companies, they can access plan designs and carrier pricing that most small and mid-size employers cannot reach on their own. According to NAPEO, businesses that use a PEO grow 7–9% faster and have 10–14% lower employee turnover than non-PEO companies.

For California employers leaving Health Net, a PEO transition accomplishes two things simultaneously: it replaces the health plan and it bundles payroll, HR administration, and workers’ compensation under one platform. Businesses working with PEOs typically save 20–40% on operation and benefit costs compared to managing HR and benefits independently.

In our experience matching hundreds of businesses across our network of 40+ vetted PEOs, California employers in the 5–100 employee range often find PEO master plans competitive with or better than what they were paying through Health Net — with broader carrier options and more plan tiers to offer employees. See our guide to best PEO options for small businesses for a deeper look at how these plans work.

OptionBest ForKey AdvantageMain Consideration
Fully Insured Group PlanGroups wanting a direct swapFamiliar structure, broad carrier choiceNetwork match varies by carrier
Level-Funded Plan10–100 employees, healthy groupPotential surplus refund, richer plan designClaims history used in underwriting
ICHRADispersed teams, cost predictabilityDefined employer cost, employee choiceEmployees manage own enrollment
PEO Master Plan5–100 employees seeking bundled HR + benefitsLarge-group pricing, multiple carrier tiersRequires PEO co-employment agreement

How Does Continuity of Care Work When a Carrier Exits?

Continuity of care is the right for employees who are mid-treatment to continue seeing their current provider temporarily, even if that provider is out-of-network with the new carrier. California law provides some continuity protections, but the scope depends on the new plan type and the carrier’s specific policies.

When evaluating replacement carriers, ask the following questions directly:

  • Does the new carrier’s California network include my employees’ current primary care physicians and specialists?
  • What is the carrier’s written policy on continuity of care for ongoing treatment (e.g., pregnancy, cancer treatment, post-surgical follow-up)?
  • How long does continuity coverage last under California Insurance Code requirements?
  • What is the process for a provider to join the network, and can we facilitate that for key employees?

Employer tip: collect a brief anonymous survey of your employees’ current providers before you finalize a carrier. Network access is the number one source of employee dissatisfaction in plan transitions, and catching mismatches before you bind coverage is far easier than resolving them afterward.

What Steps Should Employers Take Right Now?

Acting in a structured sequence reduces the risk of a coverage gap and gives your team time to absorb the transition without disruption.

Step 1: Confirm Your Current Plan Details

Pull your current Health Net group agreement and confirm the plan type, renewal date, and whether dental and vision are on the same contract. All three lines of coverage end February 28, 2027, but knowing your renewal cycle helps you sequence replacement enrollment correctly.

Step 2: Gather Your Census and Claims Data

Carriers and PEOs will ask for an employee census (name, date of birth, zip code, dependent count) and, for level-funded or self-funded options, up to 24 months of claims history. Assembling this in advance speeds up quoting significantly.

Step 3: Compare at Least Three Options Side by Side

Looking at a single replacement carrier is the most common mistake employers make in a forced transition. Seeing options side by side — fully insured, level-funded, and a PEO master plan quote — gives you a real benchmark. Our Benefits Benchmark tool shows what companies your size in California are paying for health, dental, vision, and workers’ comp.

Step 4: Evaluate Total Cost, Not Just Premium

Premium is one line item. Employer contributions, employee out-of-pocket exposure, and the administrative cost of managing open enrollment internally are all part of the total cost of a benefits program. According to the Bureau of Labor Statistics Employer Costs for Employee Compensation, health insurance represents the largest share of employer benefit costs for private-sector workers. A side-by-side view that includes administration and HR overhead often changes the ranking of options.

Step 5: Communicate Early and Clearly with Employees

Employees who hear about a carrier change from their doctor’s office before they hear it from HR lose confidence in their employer’s benefits program. Send a brief notice as soon as you know you are transitioning, explain the timeline, and commit to a date when new plan details will be available. For a broader view of how other small employers structure their benefits programs, see our small business benefits guide.

Frequently Asked Questions

Is Health Net leaving all of California or just certain regions?

Health Net of California, Inc. and Health Net Life Insurance Company are exiting California’s commercial group market statewide. The exit covers small-group and large-group medical, dental, and vision plans, with all coverage terminating February 28, 2027, per Health Net’s official exit communications and broker notices beginning September 1, 2026.

Will employees lose their doctors when Health Net exits?

Whether employees retain access to their current providers depends entirely on which replacement carrier and network you choose. Before binding a new plan, employers should run a provider directory check for each carrier under consideration and ask about California’s continuity-of-care protections for employees currently in active treatment.

Can a PEO replace Health Net group coverage for a small business?

A PEO co-employs your workforce and enrolls your employees in its master group health plan, which typically offers multiple carrier options and large-group pricing regardless of your company’s size. Based on our analysis of 40+ vetted PEOs, California employers in the 5–100 employee range frequently find PEO master plans competitive in both cost and plan design compared to standalone small-group options.

What happens if we do not replace Health Net coverage before February 28, 2027?

If no replacement coverage is bound before the termination date, your employees will be uninsured starting March 1, 2027. Employees may qualify for a Special Enrollment Period through Covered California due to loss of coverage, but employer-sponsored group coverage would no longer be in place, which creates ACA compliance exposure for applicable large employers. The IRS publishes ACA employer shared responsibility guidance at IRS.gov.

Is this a good time to renegotiate benefits or switch to a different structure?

A forced carrier transition is one of the cleaner windows to evaluate whether your current benefits structure — fully insured group, level-funded, ICHRA, or PEO master plan — is the right fit for your business size and budget. Comparing structures side by side during this transition costs no more than a direct carrier swap and often surfaces options that deliver better value for both employer and employee.


Talk through your options before the February 28, 2027 deadline.

Schedule a no-pressure consultation with the PEO Marketplace team. We will show you what fully insured, level-funded, and PEO master plan options look like for your group size and California zip code — all in one conversation.

Schedule Your Consultation →

Prefer to compare on your own timeline first. Run the Benefits Benchmark for your industry and we will email you a breakdown of what companies your size are paying for HR, benefits and workers comp.

Run the Benefits Benchmark →

Landscaping workers comp is one of the highest-cost line items for lawn care companies, and most owners are overpaying without knowing why. The combination of hazardous equipment, seasonal payroll swings, and misclassified employees creates a premium structure that punishes growth. This post breaks down exactly how to control those costs — from class codes to audit prep to master policy options.

Why Landscaping Workers Comp Costs So Much

Landscaping is classified as a high-hazard industry by the National Council on Compensation Insurance (NCCI). Workers operate power equipment — mowers, trimmers, chippers, blowers — often in physically demanding outdoor conditions. According to the Bureau of Labor Statistics, grounds maintenance workers experience injury rates well above the national average across private industries, with lacerations, strains, and heat-related illness among the most common claims. That risk profile drives base rates up before your company’s history even enters the equation.

The base rate per $100 of payroll for landscaping class codes typically runs between $6 and $14 depending on your state, compared to $1–$2 for a standard office worker. Multiply that across a 10-person seasonal crew and the premium exposure is significant. Understanding what goes into that number is the first step to managing it.

Landscaping Workers Comp Class Codes

Workers comp class codes are the foundation of your premium calculation. Misclassification — intentional or not — is one of the most common reasons landscaping companies overpay or face audit surprises. The two most relevant NCCI codes for lawn care and landscaping operations are:

  • Code 0042 – Landscaping: Covers the installation of plants, shrubs, trees, and ornamental work. This is typically the higher-rate code.
  • Code 0401 – Lawn Care: Covers routine grass cutting, fertilizing, and grounds maintenance. Generally carries a lower rate than 0042.
  • Code 8810 – Clerical: Any office staff who do not go into the field should be separately classified here at a much lower rate.

Many small landscaping operations have their entire payroll dumped into Code 0042 when a portion legitimately belongs in 0401 or 8810. A quick audit of how your carrier has classified your employees can surface savings immediately. Ask your agent or carrier for a class code breakdown on your current policy.

Overpaying for workers comp is more common than most businesses think. The PEO Calculator breaks down what you would pay through a PEO in 60 seconds.

Try the PEO Calculator →

Seasonal Payroll Swings and Why They Trigger Audit Surprises

Seasonal payroll volatility is the defining challenge for landscaping workers comp. Most traditional policies are written on estimated annual payroll, then reconciled at year-end through a premium audit. For a lawn care company that runs a full crew from April through October and a skeleton staff in winter, the gap between estimated and actual payroll can be significant in either direction.

How the Premium Audit Works Against You

At the end of your policy year, your carrier sends an auditor — in person or via mail — to review actual payroll records, subcontractor certificates, and job classifications. If your actual payroll came in higher than estimated (a common scenario when you landed new commercial contracts mid-season), you owe the difference in premium. That bill can arrive in January when cash flow is at its tightest.

Conversely, if you overestimated payroll to avoid an audit bill and your season was slower than expected, you may have prepaid premium that takes months to get back. Neither outcome is good for cash flow.

Pay-As-You-Go Workers Comp Billing

Pay-as-you-go workers comp billing solves the seasonal payroll mismatch problem directly. Instead of paying a large upfront deposit based on estimated annual payroll, premiums are calculated and charged each pay period based on actual payroll run. This approach:

  • Eliminates large year-end audit bills
  • Aligns premium payments with the revenue cycle — higher premiums in peak season, lower in winter
  • Reduces upfront deposit requirements, preserving operating capital
  • Simplifies record-keeping since payroll data feeds directly into premium calculation

Many regional carriers and professional employer organizations offer pay-as-you-go structures for landscaping businesses. It is worth asking your current carrier specifically whether this option is available on your policy.

Your Experience Modification Rate: The Number That Follows You

Your experience modification rate (EMR or X-Mod) is a multiplier applied to your base workers comp premium based on your actual claims history compared to businesses of similar size and type. An EMR of 1.0 is average. An EMR of 0.85 means you pay 15% less than average. An EMR of 1.30 means you pay 30% more — and that surcharge compounds year after year until claims age out of the calculation.

NCCI calculates the EMR annually using three years of claims data, excluding the most recent policy year. For landscaping companies, even one or two significant claims — a lost finger from a mower blade, a back injury from lifting heavy equipment — can push the EMR well above 1.0 and add thousands to premiums for the next several years.

How to Improve Your EMR

  • Manage small claims carefully. Not every minor incident needs to be filed as a claim. Understand your policy’s threshold and consider paying small medical costs out of pocket when it makes actuarial sense.
  • Return injured workers to modified duty quickly. Lost-time claims weigh more heavily in the EMR formula than medical-only claims. A light-duty return-to-work program can convert a lost-time claim into a medical-only claim and reduce its impact significantly.
  • Dispute inaccurate claims data. EMR calculations depend on data submitted by your carrier to NCCI. Errors happen. Review your unit statistical report annually and dispute incorrect entries through the NCCI dispute resolution process.

Safety Programs That Actually Move the Needle for Landscaping Crews

A documented safety program is one of the few levers landscaping owners control directly. Carriers reward consistent safety investment both in underwriting decisions and in some schedule credit programs. More importantly, fewer injuries mean fewer claims, which protects your EMR over time.

High-Impact Safety Practices for Lawn Care Operations

Risk AreaCommon Injury TypeRecommended Control
Mower operationLacerations, amputationsPre-operation checklist, blade guards, PPE policy
Manual material handlingStrains, back injuriesLift training, team lifts for loads over 50 lbs
Heat exposureHeat exhaustion, strokeHydration breaks, shade access, heat index monitoring
Chemical handlingSkin and eye irritationSDS on-site, gloves, eye protection, applicator training
Truck and trailer operationMVA, falls from trailerMVR checks at hire, trailer load securement policy

The Occupational Safety and Health Administration (OSHA) provides sector-specific guidance for landscaping and grounds maintenance operations at osha.gov. A written safety program does not need to be complex to be effective — consistency in toolbox talks, incident reporting, and equipment inspection matters more than document length.

How PEO Master Policies Work for Landscaping Companies

A Professional Employer Organization (PEO) is a co-employment arrangement where your employees are added to the PEO’s master payroll. One of the most significant financial benefits for landscaping businesses is access to the PEO’s master workers comp policy.

Rather than purchasing your own standalone policy — where your EMR and your class codes determine your rate — your employees are covered under the PEO’s group policy. The PEO negotiates carrier rates based on the aggregate experience of its entire client base, which often numbers in the tens of thousands of employees. According to the National Association of Professional Employer Organizations (NAPEO), PEO clients grow 7–9% faster and have 10–14% lower employee turnover than comparable non-PEO businesses. Workers comp cost management is a key driver of that financial performance.

What Changes Under a PEO Workers Comp Policy

  • Your EMR is set aside. You are covered under the PEO’s master policy, so your individual experience mod no longer determines your rate directly. This is especially valuable for landscaping businesses with a poor claims history that is currently inflating premiums.
  • Pay-as-you-go is built in. PEOs run payroll, so workers comp premiums are calculated per pay period automatically — no annual deposit, no audit surprise.
  • Claims management is handled by the PEO. PEOs have dedicated risk and claims teams who manage open claims, work with adjusters, and implement return-to-work programs. Faster claims closure protects future rates.
  • Safety resources are included. Most PEOs provide OSHA compliance tools, safety training libraries, and incident reporting systems as part of their platform.

The tradeoff is that a PEO relationship is broader than just workers comp — it includes payroll, HR administration, and often benefits. For businesses that want the coverage benefit without the full co-employment structure, a standalone pay-as-you-go policy or a captive insurance arrangement may be more appropriate. Based on our analysis of 40+ vetted PEOs, the break-even point where the master policy advantage outweighs the administration fee typically sits around 5–10 employees for landscaping companies with above-average EMRs.

Businesses that want to compare standalone workers comp options alongside PEO master policy pricing side by side can review the considerations in our best PEO for small business guide, or run numbers through the PEO Calculator to see estimated cost comparisons for your crew size.

Is a PEO the Right Fit for a Seasonal Lawn Care Business

Seasonal employment creates one additional consideration: some PEOs are more accommodating than others when it comes to rehiring the same seasonal employees each spring, managing variable headcount, and handling unemployment exposure across states. When evaluating PEOs for a landscaping operation, ask specifically about seasonal payroll flexibility, re-hire workflows, and whether the minimum employee count applies year-round or just during active payroll periods. Our team has matched landscaping and green-industry businesses with PEOs that specialize in this exact profile — you can explore the matching process at Find Your PEO.

For a detailed look at how specific PEO costs compare, the Insperity cost comparison breaks down pricing structures across major providers, which can serve as a useful benchmark when evaluating workers comp-inclusive arrangements.


Summary: Where Landscaping Companies Lose on Workers Comp

Most landscaping businesses overpay on workers comp for one or more of the following reasons: incorrect class code assignments, an elevated EMR from prior claims, traditional billing structures that create audit exposure, and limited access to group-rate policies. Each of these is addressable. Class codes can be reviewed annually. EMR improves with disciplined claims management and safety investment. Pay-as-you-go billing eliminates audit uncertainty. And PEO master policies offer a structural reset for businesses whose standalone history is working against them.

The IRS and Department of Labor both publish guidance relevant to co-employment and employer tax obligations under PEO arrangements — IRS.gov and DOL.gov are the authoritative sources for compliance questions specific to your situation.

Talk to a PEO Specialist

PEO Marketplace works with 40+ vetted PEOs and matches landscaping and lawn care businesses with the right fit based on crew size, state, and seasonal payroll structure. Schedule a no-pressure consultation to review your workers comp situation and see what options are available.

Schedule a Consultation →

Prefer to compare on your own timeline first. Run the Benefits Benchmark for your industry and we will email you a breakdown of what companies your size are paying for HR, benefits and workers comp.

Run the Benefits Benchmark →


Frequently Asked Questions

What class code covers lawn mowing for workers comp purposes?

Routine lawn mowing and grounds maintenance typically falls under NCCI Class Code 0401 (Lawn Care), which carries a lower base rate than Code 0042 (Landscaping). Businesses that do both types of work should ensure their payroll is split correctly between these codes, because assigning all payroll to 0042 results in higher premiums than necessary.

How does a seasonal workforce affect workers comp premiums?

Seasonal payroll fluctuations create a mismatch between estimated and actual premium when using traditional annual policies, which often results in an unexpected audit bill at year-end. Pay-as-you-go billing resolves this by tying premium payments directly to each actual payroll run, so amounts due track the natural peak-and-trough cycle of a lawn care business.

Can a high experience mod be reduced?

An elevated experience modification rate can be reduced over time by preventing new claims, closing open claims quickly, implementing a return-to-work program for injured employees, and disputing any inaccurate data in the NCCI unit statistical report. The EMR calculation uses three years of claims history, so improvement takes time but each clean policy year moves the number in a favorable direction.

What is a PEO master workers comp policy?

A PEO master workers comp policy is a group insurance policy held by the professional employer organization that covers all employees across its client base under one arrangement. Landscaping businesses that join a PEO are covered under this master policy rather than their own standalone policy, which means the client company’s individual experience mod is set aside and premiums are based on the PEO’s group rates.

Is pay-as-you-go workers comp available without a PEO?

Pay-as-you-go workers comp billing is available through some traditional carriers and independent agents without entering a PEO arrangement, though availability varies by state and carrier. A PEO automatically provides this structure because payroll and workers comp administration are integrated within the same platform, but standalone pay-as-you-go policies are a viable option for businesses that only want to address the billing structure without the full co-employment model.

For small businesses with 20 to 80 employees, the question of whether to hire an HR person or outsource HR comes down to cost, coverage, and where you are in your growth stage. A dedicated HR manager gives you someone in-house, but costs $65,000–$95,000 per year before benefits and overhead. HR outsourcing runs $80–$130 per employee per month and often covers more ground from day one. Neither answer is right for every business — but this guide will help you figure out which is right for yours.

Why Your HR Decision Matters More Than You Think

HR is not just paperwork. At 20 to 80 employees, you are past the stage where the owner or office manager can juggle hiring, compliance, benefits administration, and payroll on the side. Employment law violations, mis-classified workers, and benefits gaps are expensive mistakes. According to the U.S. Department of Labor, wage and hour violations alone cost employers hundreds of millions in back pay each year — and small businesses are not exempt.

The 20-to-80-employee window is also where turnover gets costly. Replacing an employee costs 50–200% of their annual salary depending on the role. Without proper HR infrastructure — onboarding, performance management, competitive benefits — you are more exposed than you realize.

So the decision is not really “do we need HR?” It is “how do we get HR done in the most effective and cost-efficient way?”

Not sure if a PEO makes sense for your business? Our free calculator shows you the real cost in 60 seconds — no call, no email, no commitment.

Try the Free Calculator →

Option 1: Hiring an In-House HR Manager

Hiring your first HR person means bringing on a dedicated employee whose full-time job is managing your people operations. Here is what that actually costs and covers.

What Does an HR Manager Cost?

The base salary for an HR manager at a small business typically falls between $65,000 and $95,000 per year depending on your market and their experience level. According to the Bureau of Labor Statistics, the median annual wage for HR managers is around $136,000 nationally — but small business hires typically land at the lower end of the spectrum, trading comp for culture and ownership.

The “loaded” cost — salary plus payroll taxes, health insurance, PTO, 401(k) match, and overhead — adds 25–40% on top of base salary. That means a $75,000 HR manager actually costs you $94,000–$105,000 per year when all is said and done.

What an HR Manager Can and Cannot Do

A single HR generalist is excellent at relationship-based work: recruiting, onboarding, employee relations, and day-to-day questions. They know your people and your culture. But one person cannot be an expert in everything — employment law across multiple states, benefits procurement, workers’ compensation audits, payroll tax compliance, and HR technology all require deep specialization.

At 20–50 employees, you will likely also need to keep a payroll provider (like Gusto or ADP) and a benefits broker on retainer, since most HR generalists are not set up to handle those independently. That adds cost and complexity.

When an In-House HR Hire Makes Sense

  • You have 60+ employees and HR demands are genuinely full-time
  • You have complex employee relations issues that need a consistent, on-site presence
  • Your culture and employer brand are a competitive differentiator that needs dedicated stewardship
  • You are scaling rapidly and need someone fully embedded in leadership decisions

Option 2: HR Outsourcing — What It Is and How It Works

HR outsourcing means contracting with an outside firm to handle some or all of your HR functions. This can range from a simple HR software platform to a full-service arrangement that covers payroll, benefits, compliance, and more.

Types of HR Outsourcing

There are a few distinct models worth understanding:

  • HR Software Platforms (HRISs): Tools like Gusto, Rippling, or BambooHR automate payroll and basic HR admin. Cost: $8–$25 per employee per month. These are tools, not advisors — someone still needs to manage them.
  • HR Consulting / Fractional HR: You hire an outside HR professional on a part-time or project basis. Cost: $50–$150 per hour or flat retainers. Good for specific problems, not ongoing management.
  • HR Outsourcing Firms (HROs): Third-party firms take over specific HR functions like benefits administration or compliance support. Cost: $80–$130 per employee per month depending on scope.
  • Professional Employer Organizations (PEOs): A PEO co-employs your workforce and handles payroll, benefits, workers’ comp, and compliance under one roof. Cost: typically $80–$150 per employee per month or 2–8% of total payroll. This is the most comprehensive outsourcing option available to small businesses.

What Does HR Outsourcing Cover That a Single Hire Cannot?

The biggest advantage of outsourcing is depth. When you hire one HR manager, you get one person’s knowledge. When you outsource to a firm or PEO, you get a team of specialists — benefits experts, compliance attorneys, payroll specialists, and HR advisors — for less than the cost of that single hire.

For a company with 30 employees paying $100 per employee per month, that is $3,000/month or $36,000/year. Compare that to $94,000+ for a loaded HR manager salary — and you can see why outsourcing is attractive at the 20–60 employee stage.

The PEO Option: Full-Service HR Outsourcing Built for Small Business

A Professional Employer Organization (PEO) is the most complete form of HR outsourcing available to small and mid-size businesses. A PEO becomes a co-employer of your workforce, which means it handles payroll processing, tax filings, benefits administration, workers’ compensation, and compliance — all under one contract.

How Does a PEO Work?

You retain full control of your business decisions: who you hire, how you manage your team, what roles exist. The PEO takes on the administrative employer responsibilities. Your employees get access to Fortune 500-level benefits — medical, dental, vision, 401(k) — that a small business could never negotiate on its own, because the PEO pools hundreds of client companies together for group purchasing power.

According to NAPEO (the National Association of Professional Employer Organizations), businesses that use PEOs grow 7–9% faster and have 10–14% lower employee turnover than comparable businesses that do not. PEO clients also have a lower rate of business failure — a meaningful stat for companies in the 20–80 employee range where execution problems can be fatal.

Based on our analysis of 100+ PEO providers at PEO Marketplace, PEOs are most cost-effective for businesses with 10–150 employees who do not yet have the headcount to justify a full HR department but need real infrastructure.

Want to see how providers compare? Check out our breakdown of Gusto vs. Justworks vs. full-service PEOs or our Insperity cost comparison to see how pricing stacks up across the market.

Side-by-Side Cost Comparison

HR ApproachAnnual Cost (30 Employees)CoverageBest For
In-House HR Manager$94,000–$120,000 loadedGeneralist support, culture, ER60+ employees, complex culture needs
HR Software Only$3,000–$9,000/yrPayroll automation, basic adminUnder 20 employees with low complexity
HRO / Fractional HR$36,000–$47,000/yrSpecific functions; piecemeal25–50 employees, targeted needs
PEO (Full-Service)$36,000–$54,000/yrPayroll, benefits, compliance, workers’ comp, HR support20–150 employees wanting full HR infrastructure

Cost estimates for a 30-employee company. PEO pricing assumes $100–$150 per employee per month. HR manager loaded cost includes salary, taxes, and benefits at 25–35% uplift.

How to Decide: A Simple Framework

In our experience matching hundreds of businesses with the right HR solution, the decision usually breaks down along a few key questions:

Choose HR Outsourcing (or a PEO) if:

  • You have fewer than 60 employees and cannot justify a full-time HR salary
  • You want access to enterprise-grade benefits to compete for talent
  • You operate in multiple states with varying compliance requirements
  • You want to reduce your liability exposure without building an internal legal/HR team
  • Your leadership team is stretched thin and needs to offload administrative burden fast

Choose an In-House HR Hire if:

  • You have 60–80+ employees and HR is genuinely a full-time operational need
  • You have complex, ongoing employee relations situations that need a present, known face
  • You have budget to pay competitively and want to invest in culture long-term
  • You are planning to scale significantly and want HR embedded in leadership

Note: many businesses use both. A PEO handles the administrative heavy lifting, while a part-time or fractional HR person manages culture, recruiting, and day-to-day people questions. It is not always an either/or decision.

If you are not sure where your business falls, our guide to the best PEOs for small businesses breaks down options by company size, and our free PEO matching service can walk you through what fits your situation.

What Most Business Owners Get Wrong About This Decision

The most common mistake we see is comparing the cost of outsourcing to the cost of a single HR salary — without accounting for what that salary does not cover. One HR manager does not include group health insurance purchasing power, workers’ comp management, multi-state compliance expertise, or HRIS technology. When you add those costs back in, outsourcing almost always wins on value at the 20–60 employee stage.

The second mistake is waiting too long. Many business owners put off the HR decision until there is a crisis — a termination gone wrong, an ADA complaint, an I-9 audit. At that point, the cost of fixing a problem far exceeds what structured HR would have cost to prevent it.

Use our PEO cost calculator to run your own numbers — it takes 60 seconds and gives you a realistic side-by-side comparison for your headcount and industry.


Ready to Figure Out the Right HR Path for Your Business?

Whether you are leaning toward your first HR hire, exploring outsourcing options, or trying to understand whether a PEO is worth the cost, we can help you map it out. PEO Marketplace works with 100+ vetted providers and matches businesses for free — no pressure, no commissions from you.

Book a Free 15-Minute Consultation →

Not ready to book a call? Get a free Benefits Benchmark Report for your industry — we will email you a breakdown of what companies your size are paying for HR, benefits, and workers comp so you can compare on your own timeline.

Get My Free Benchmark Report →


Frequently Asked Questions

At what employee count should I hire an HR person?

Most small businesses are ready for a dedicated in-house HR hire between 60 and 80 employees, when HR demands clearly exceed what one generalist can handle on the side. Below that threshold, HR outsourcing or a PEO typically delivers more coverage at lower cost than a full-time salary.

What is the difference between an HRO and a PEO?

An HRO (HR outsourcing firm) handles specific HR functions you assign to them, while a PEO becomes a co-employer and takes comprehensive responsibility for payroll, benefits, compliance, and HR administration under one agreement. PEOs offer more integrated coverage and typically provide access to better group benefit rates than a standalone HRO.

How much does HR outsourcing cost per employee?

HR outsourcing generally runs $80–$130 per employee per month for most small businesses, depending on the scope of services and the size of your workforce. Full-service PEOs may range from $80–$150 per employee per month, or 2–8% of total payroll, and typically include benefits, payroll, workers’ comp, and compliance support.

Can a PEO replace an HR manager completely?

A PEO handles the administrative and compliance-heavy functions of HR — payroll, benefits, tax filings, workers’ comp — but does not replace the relationship-based and culture-building work that an in-house HR person provides. Many growing companies use a PEO for infrastructure while keeping a part-time or fractional HR person for employee relations and recruiting.

Is HR outsourcing risky for a small business?

Working with a reputable, certified PEO or HRO is generally lower risk than managing HR internally with limited expertise, because these firms specialize in compliance and employ teams of HR and legal specialists. Look for PEOs that are ESAC-accredited or IRS-certified, which signals financial stability and operational accountability.

Small businesses pay 20–40% more for worse health insurance than large employers — and that benefits gap is quietly driving your best people out the door. The good news is there’s a proven way to close that gap without becoming a Fortune 500 company. Small business employee benefits can be dramatically upgraded through a strategy called PEO group pooling, which gives companies of any size access to the same insurance purchasing power as employers with thousands of workers.

The Moment You Realize You’re Losing on Benefits

Picture this: You’ve spent three years growing a sharp, loyal operations manager from entry-level into one of your most valuable people. She knows your systems, your clients, your quirks. Then one Thursday afternoon, she comes into your office and gently closes the door behind her.

She’s leaving. Not for a role that’s more interesting. Not even for a huge pay bump. She’s leaving because the company down the road — the one with 800 employees and a regional headquarters — is offering her a health plan with a $500 deductible instead of $4,000, a 401(k) with a 4% match, and dental and vision coverage that doesn’t feel like an afterthought.

You tried. You’ve been offering benefits since year two. But competing on benefits as a 20-person company feels like bringing a bike to a drag race.

If this story sounds familiar, you’re not alone — and more importantly, it’s not your fault. It’s a structural problem baked into how small business employee benefits have traditionally been priced and packaged.

Why Small Businesses Are Fighting an Unfair Benefits Battle

The core issue is purchasing power. Insurance carriers price health plans based on risk pools — the larger the group, the more risk gets spread out, and the lower the per-employee cost. A company with 5,000 employees negotiates dramatically better rates than a company with 25 employees, even if both workforces are equally healthy.

According to the Kaiser Family Foundation Employer Health Benefits Survey, small firms (under 200 employees) pay an average of 8–18% more in premiums per employee than large firms — and that gap widens significantly when you factor in plan quality, deductibles, and out-of-pocket maximums. Some analysis puts the real total cost disparity — when you account for what employees actually experience — closer to 20–40%.

That means your employee isn’t just seeing a better-looking benefits package at the bigger company. They’re seeing a genuinely better product that costs you more to deliver less of.

The Retention Data Is Hard to Ignore

This isn’t a soft, anecdotal problem. According to SHRM’s Employee Benefits research, health insurance is consistently ranked the #1 most important benefit by employees — above paid time off, retirement plans, and flexibility. SHRM also reports that 56% of employees say benefits quality is a major factor in deciding whether to stay with an employer.

Meanwhile, the Bureau of Labor Statistics consistently shows that employees at smaller firms have shorter average tenure than those at larger organizations. The reasons are complex, but compensation and benefits gaps are among the most frequently cited factors.

When you’re spending 30–50% of a role’s salary to replace someone who left for better benefits, this stops being an HR issue and becomes a business survival issue.

What Your Employees Are Comparing You To

Your employees aren’t just comparing their benefits to your competitors in your industry. They’re comparing to every employer in their network — friends’ jobs, LinkedIn posts, recruiting emails. And in a labor market where large employers have invested heavily in benefits communication and transparency, the contrast is sharp.

A $4,000 deductible health plan looks terrible next to a $500 deductible plan — even if your total compensation is competitive. People viscerally understand what a medical bill feels like. They don’t always do the math on salary differentials.

Wondering if a PEO could get your team better benefits for less? Run the numbers yourself — our free calculator shows you what companies your size are actually paying.

Try the Free Calculator →

What Is a PEO and How Does It Fix the Benefits Gap?

A Professional Employer Organization (PEO) is a co-employment arrangement where a third-party firm becomes the employer of record for your workforce, allowing your employees to be covered under the PEO’s large-group benefits plans. In plain terms: your 20-person team gets access to the same insurance pool as a company with tens of thousands of employees.

This is called group pooling, and it’s the single most powerful tool available to small businesses trying to compete on benefits. By aggregating workers from hundreds or thousands of small business clients, a PEO creates a massive risk pool that commands Fortune 500-level insurance rates from carriers like UnitedHealthcare, Aetna, BlueCross BlueShield, and others.

How PEO Group Pooling Works in Practice

When you join a PEO, your employees become part of the PEO’s master health plan. Instead of your broker going to market with 20 employees and getting mediocre rates, the PEO negotiates for the entire pool — which might be 50,000 or 100,000+ employees combined. The carrier gives dramatically better rates and plan designs because the volume and risk distribution justify it.

According to NAPEO (the National Association of Professional Employer Organizations), businesses that use PEOs grow 7–9% faster, have 10–14% lower employee turnover, and are 50% less likely to go out of business than comparable businesses that don’t. A significant driver of that retention improvement is the benefits quality upgrade.

What Benefits Can a PEO Actually Offer?

Based on our analysis of 100+ PEO providers at PEO Marketplace, here’s what small businesses typically gain access to through PEO co-employment:

Benefit CategoryTypical Small Biz (Going It Alone)Through a PEO
Health Insurance Deductible$3,000–$6,000$500–$1,500
Plan Choices1–2 options3–10+ options (HMO, PPO, HDHP)
Dental & VisionOften not offered or low qualityIncluded, name-brand carriers
401(k) with MatchRare or basicStandard, low admin cost
Life & Disability InsuranceRarely includedOften bundled
HR & Compliance SupportDIY or expensive consultantIncluded in most PEO arrangements

Is a PEO the Right Move for Your Business?

PEOs work best for companies with 5–500 employees that are experiencing real hiring or retention friction related to benefits. If you’ve lost a good person to a larger competitor in the past 12 months and benefits were part of the conversation — even a small part — it’s worth running the numbers.

Most business owners are surprised to find that a PEO arrangement costs roughly the same as managing HR and benefits independently, once you factor in the cost of your time, compliance risk, and the premium difference. In many cases, you come out ahead financially while offering a dramatically better benefits package. You can explore our guide to the best PEOs for small businesses to see which providers tend to perform best for companies your size.

Not All PEOs Are Created Equal

This is where working with an independent advisor matters. In our experience matching hundreds of businesses to PEO providers at PEO Marketplace, we’ve seen significant variation in plan quality, carrier access, pricing transparency, and customer service. A PEO that’s great for a 15-person tech startup may be the wrong fit for a 75-person manufacturing company.

If you want to benchmark what you’re currently paying against what’s available through PEOs, our free Benefits Benchmark Report shows you exactly what companies your size and industry are paying — no sales pressure required. You can also use our PEO matching tool to get a shortlist of vetted providers that fit your specific situation.

What to Watch Out For

A few honest caveats from our side of the table: PEOs involve a co-employment relationship, which means the PEO becomes the employer of record for certain HR and payroll purposes. Some business owners are initially uncomfortable with this structure. It’s worth understanding the legal and operational implications before you sign anything. Also, not every PEO offers the same level of plan flexibility — some have more restrictive carrier relationships that limit your options. Always ask to see the actual plan designs and carrier names before committing.

The Real Cost of Doing Nothing

Let’s be direct: every month you delay solving your benefits problem is another month your competitors have an edge in recruiting and retention. SHRM estimates the average cost of replacing an employee is 50–200% of their annual salary when you include recruiting, onboarding, and lost productivity. A single mid-level hire replacement can easily run $15,000–$30,000.

Compare that to the cost of upgrading your benefits through a PEO — often a few hundred dollars per employee per month, sometimes offset by savings on what you’re already paying. The math tends to favor action.

If you want to see exactly how the numbers stack up for your team, our free PEO cost calculator gives you a real estimate in minutes based on your headcount, industry, and current benefits spend.


Take the Next Step

You’ve built something worth working for. The talent that leaves for bigger companies isn’t leaving because they don’t value what you’ve created — they’re leaving because the system has been tilted against you. PEO group pooling levels that playing field.

Ready to see what your business qualifies for? Book a free, no-pressure consultation with one of our PEO advisors. We’ll review your current benefits setup, benchmark it against the market, and tell you honestly whether a PEO makes sense for your situation.

Book a Free Benefits Strategy Call →

Not ready to book a call? Get a free Benefits Benchmark Report for your industry — we will email you a breakdown of what companies your size are paying for HR, benefits, and workers comp so you can compare on your own timeline.

Get My Free Benchmark Report →


Frequently Asked Questions

Why do small businesses pay more for worse health insurance than large companies?

Health insurance carriers price premiums based on risk pools — larger groups spread risk across more people, which lowers per-employee costs and allows carriers to offer better plan designs. A small business with 20 employees has almost no negotiating leverage with carriers, while a company with 5,000 employees can command significantly better rates and lower deductibles. This structural disadvantage means small businesses routinely pay 20–40% more for plans with higher deductibles and fewer options than their larger competitors offer.

What is PEO group pooling and how does it help small businesses?

PEO group pooling is when a Professional Employer Organization combines the employees of hundreds or thousands of small business clients into a single large-group insurance pool, allowing each individual small business to access the same negotiated rates and plan quality as a large employer. Because the PEO negotiates on behalf of a pool that may include tens of thousands of workers, it can secure name-brand carrier plans with low deductibles and broad coverage that a 20-person company could never access on its own. This is the core mechanism that allows small businesses to offer Fortune 500-level benefits.

How much does it cost to join a PEO?

PEO pricing typically ranges from $80–$200 per employee per month, or 2–12% of total payroll, depending on the provider, your company size, and the services included. In many cases, the savings on health insurance premiums and the elimination of separate HR software, compliance, and payroll costs offset a significant portion of the PEO fee — meaning the net cost is often lower than what you’re already spending. Use our free PEO cost calculator to get an estimate tailored to your headcount and industry.

Will joining a PEO mean I lose control of my business?

No — a PEO co-employment arrangement means the PEO becomes the employer of record for payroll and benefits administration purposes, but you retain full control over hiring, firing, day-to-day management, and business strategy. Think of it as outsourcing the administrative employer role while keeping all operational authority. The co-employment structure is well-established legally and is used by over 200,000 businesses across the United States according to NAPEO.

How do I know which PEO is right for my small business?

The right PEO depends on your industry, headcount, location, and specific benefits priorities — there’s no universal best option. Based on our analysis of 100+ PEO providers, we recommend comparing at least two or three vetted options side by side on plan quality, pricing transparency, HR support depth, and client service reputation. You can explore our guide to the best PEOs for small businesses or use our free PEO matching tool to get a personalized shortlist in minutes.

Full-service payroll with benefits means handling employee pay, health insurance, workers’ comp, and HR compliance through a single provider or coordinated system — not juggling four different vendors. Most small businesses cobble this together piecemeal and overpay as a result. This guide breaks down every model on the market, what each one actually costs, and which one delivers the most value for businesses with 5 to 200 employees.

Why “Payroll Plus Benefits” Is Harder Than It Sounds

When business owners search for full-service payroll with benefits, they typically picture a single dashboard: run payroll, manage health insurance, handle tax filings, stay compliant. Simple. The reality is that most payroll software companies are not licensed insurance carriers, and most benefits brokers don’t touch payroll. That gap forces you to become the integration layer — manually reconciling deductions, chasing down W-2s, and navigating compliance questions that fall between vendor desks.

There are three real models in this market. Each has a different cost structure, a different risk profile, and a different ceiling on what it can actually deliver.

Model 1: Standalone Payroll Software + Separate Benefits Broker

This is how most small businesses start. You sign up for Gusto, ADP Run, or Paychex Flex to handle payroll. You work with an independent broker to shop health plans. You either self-manage workers’ comp or buy a separate policy. On paper it looks affordable. In practice, costs stack up fast:

  • Payroll software: $40–$150/month base + $6–$12 per employee
  • Benefits broker: Often commission-based (1–5% of premium), sometimes a flat fee of $1,000–$3,000/year for small groups
  • Workers’ comp: Purchased separately, typically 1–5% of payroll depending on industry
  • HR compliance tools or attorney fees: Ad hoc, often $500–$2,500/year when issues arise

For a company with 20 employees paying average wages, you’re easily looking at $8,000–$18,000 per year in vendor costs alone — before you account for the internal time spent managing all of it. And because you’re a small group shopping health insurance independently, you’re paying retail rates. A 20-person company buying health insurance on its own has almost zero negotiating leverage with carriers.

If you want a deeper look at how Gusto stacks up in this space, our breakdown of Gusto vs. Justworks vs. PEO covers exactly where each platform draws the line on benefits support.

Wondering if a PEO could get your team better benefits for less? Run the numbers yourself — our free calculator shows you what companies your size are actually paying.

Try the Free Calculator →

Model 2: Bundled HR Software Platforms (Rippling, Bamboo, Deel)

A step up from pure payroll software, platforms like Rippling or Bamboo HR bundle payroll, basic HR tools, and benefits administration into one interface. They’re genuinely better than managing three separate logins. But there’s a critical distinction: these platforms administer benefits — they don’t underwrite them. You’re still a small employer buying insurance at small-group rates. The platform just makes it easier to manage the paperwork.

Costs here run $8–$20 per employee per month for the core HR and payroll stack, with benefits administration layered on top. A 25-person company might pay $400–$600/month for the platform, which sounds reasonable — until you realize your health insurance premiums haven’t changed at all because your risk pool is still 25 people.

Model 3: Professional Employer Organization (PEO)

A PEO is the only model that fundamentally changes your buying power for benefits. Here’s why: under a co-employment arrangement, your employees join the PEO’s master health plan alongside thousands of other workers. You’re no longer a 20-person company shopping for health insurance — you’re part of a group that might have 50,000 covered lives. That changes your premiums, your plan options, and your carrier access in ways that no software platform can replicate.

According to NAPEO, companies that use PEOs grow 7–9% faster and have 10–14% lower employee turnover than comparable businesses that don’t. Those numbers aren’t just about HR efficiency — they reflect what happens when small businesses can compete with large employers on total compensation.

A PEO bundles into a single per-employee-per-month (PEPM) fee or a percentage of payroll:

  • Full-service payroll processing and tax filing
  • Access to Fortune-500-level health, dental, vision, and life insurance plans
  • Workers’ compensation coverage (often at significantly reduced rates)
  • HR compliance support — handbooks, federal and state compliance, ACA reporting
  • 401(k) options with institutional pricing
  • Dedicated HR support staff

Total PEO costs typically run $80–$180 per employee per month all-in, including the service fee. For a company with 15–50 employees, the savings on health insurance premiums and workers’ comp alone frequently offset the entire PEO service fee — making it cost-neutral or cost-positive before you factor in time savings.

Head-to-Head Cost Comparison: 25-Employee Company

To make this concrete, here’s what full-service payroll with benefits actually costs across all three models for a 25-person business in a mid-cost metro, based on our analysis of 100+ PEO providers and standard market pricing:

Cost CategoryStandalone Payroll + BrokerBundled HR PlatformPEO
Payroll Processing$150–$400/moIncluded in platformIncluded in PEPM
Health Insurance (employer share)$12,000–$20,000/yr (small group rates)$12,000–$20,000/yr (small group rates)$9,000–$16,000/yr (large group rates)
Workers’ Comp$3,000–$8,000/yr$3,000–$8,000/yr$1,500–$5,000/yr (group rates)
HR Compliance / Support$500–$2,500/yr (ad hoc)Limited, includedFully included
Platform / Service Fee$1,800–$4,800/yr$3,600–$7,200/yr$6,000–$15,000/yr
Estimated Annual Total$17,000–$36,000$19,000–$36,000$17,000–$36,000
HR Time BurdenHigh (owner/HR staff)MediumLow (dedicated HR team)

Note: Health insurance savings under a PEO vary significantly by industry, employee demographics, and location. The ranges above reflect typical employer-share contributions at 70% coverage. Your actual numbers will differ.

The total cost column looks similar across models at a glance — but that obscures what you actually get. The PEO delivers dedicated HR support, compliance coverage, and better plan quality within the same budget. The standalone model gives you vendor management headaches and retail insurance pricing for roughly the same spend.

What Full-Service Payroll With Benefits Actually Requires

Before choosing a model, it’s worth being clear on what “full service” should mean. According to the U.S. Department of Labor, employer-sponsored health coverage carries specific compliance obligations — ERISA filings, COBRA administration, ACA reporting for employers with 50+ ALE employees, and state-specific mandates. Payroll compliance is equally demanding: the IRS requires accurate quarterly 941 filings, proper classification of employees vs. contractors, and timely tax deposits. Missing either area creates real liability.

A PEO handles both as part of the service. Standalone payroll software handles payroll taxes — but not benefits compliance. Bundled HR platforms handle benefits admin — but typically don’t assume fiduciary responsibility for plan compliance. That distinction matters more than most business owners realize until something goes wrong.

Which Model Is Right for Your Business?

Standalone Payroll + Broker: Best for 1–10 employees

If you have fewer than 10 employees and limited benefit needs, starting with Gusto or ADP Run plus a local broker is reasonable. You won’t have much insurance buying power at this size regardless of the model, and a PEO service fee may not pencil out until you’re larger.

Bundled HR Platform: Best for tech-forward companies prioritizing UX

If your team is distributed, you value integrations with other software, and your primary pain point is administrative complexity (not insurance cost), a platform like Rippling can make sense. Just understand you’re still buying benefits at small-group rates.

PEO: Best for 10–200 employees who want real cost savings and compliance coverage

Based on our experience matching hundreds of businesses to PEO providers, companies in the 10–200 employee range see the clearest ROI from a PEO. You’re large enough to make the service fee worthwhile, and small enough that the group rate savings on health insurance are significant compared to what you’d pay independently.

If you’re not sure whether the math works for your business, our free PEO cost calculator runs the numbers based on your employee count, industry, and current benefits spend. And if you want to see how specific PEOs compare on pricing and service, our best PEO for small business guide covers the top providers in detail.

Not sure what you should be paying for benefits in your industry? Our Benefits Benchmark Report gives you a free breakdown of what companies your size are actually spending — so you can evaluate any quote you receive against real market data.

FAQ: Full-Service Payroll With Benefits

What is full-service payroll with benefits?

Full-service payroll with benefits refers to a solution that handles employee payroll processing, tax filings, and employer-sponsored benefits — including health insurance, workers’ comp, and sometimes retirement plans — through one provider or coordinated system. The most complete version of this model is a Professional Employer Organization (PEO), which bundles all of these services into a single co-employment arrangement.

Does Gusto offer full-service benefits with payroll?

Gusto offers benefits administration alongside payroll, meaning it helps you manage and enroll in health plans through its platform. However, Gusto does not change your insurance buying power — you’re still a small employer purchasing coverage at small-group rates. A PEO, by contrast, pools you with thousands of other businesses to access large-group pricing.

How much does full-service payroll with benefits cost per employee?

Costs vary significantly by model. Standalone payroll software runs $6–$12 per employee per month, not including benefits premiums. Bundled HR platforms run $8–$20 PEPM. A PEO typically runs $80–$180 PEPM all-in — but that fee often includes workers’ comp, HR compliance support, and access to lower insurance premiums that can offset the cost entirely.

Is a PEO the same as a payroll company?

No — a PEO does much more than process payroll. Under a co-employment model, a PEO becomes the employer of record for tax and benefits purposes, allowing your employees to access Fortune-500-level benefit plans and shifting significant compliance liability to the PEO. Payroll companies process wages and file taxes but do not assume co-employer status or provide access to group insurance pools.

At what company size does a PEO make financial sense?

In our experience matching businesses to PEOs, the ROI typically becomes clear at 10 or more employees, and grows stronger through 200 employees. Below 10, the service fee may outweigh the benefits savings. Above 200, some companies find they have enough internal HR capacity and buying power to justify self-managing — though many still use PEOs for compliance risk transfer and administrative efficiency.

Find the Right Payroll and Benefits Solution for Your Business

We’ve vetted 100+ PEO providers so you don’t have to. In a free 30-minute call, we’ll match you with the right solution for your size, industry, and budget — at no cost to you.

Book Your Free Consultation →

Not ready to book a call? Get a free Benefits Benchmark Report for your industry — we will email you a breakdown of what companies your size are paying for HR, benefits, and workers comp so you can compare on your own timeline.

Get My Free Benchmark Report →

Scroll to Top